Selling a FiDi condo with high common charges is not a single pricing problem. It is a monthly-cost, building-finance, tax, insurance, and financing story. Explain what the number buys, test whether it is sustainable, and price the unit against realistic alternatives.
For neighborhood context, see Brett’s Selling a Condo in the Financial District 2026 guide. Then treat your building as its own market. A FiDi tower with a staffed lobby, extensive amenities, commercial space, a ground lease, or a major capital program cannot be valued from a neighborhood median alone.
Selling a FiDi Condo With High Common Charges: Explain the Bill
Common interest sets the starting allocation
New York’s Condominium Act generally charges common expenses according to each unit’s common interest. The declaration and bylaws may authorize special allocations for nonresidential units or special or exclusive use or control. Insurance has a separate statutory allocation rule. Similar-sized apartments can therefore have different charges.
The percentage is the legal share used to allocate common obligations, subject to the documents. Obtain the declaration, bylaws, amendments, and current schedule before describing a charge as unfair, temporary, or unusually high.
Operating expenses are only one layer
The operating budget can pay for payroll, management, cleaning, heat, water, electricity in common areas, elevators, repairs, security, concierge service, landscaping, legal and accounting work, and routine contracts. A full-service building can cost more to operate than a smaller building with fewer staff and amenities. Commercial or retail areas can also add accounting, access, insurance, and maintenance complexity.
A reserve allocation sets money aside for future capital needs such as roofs, façades, elevators, boilers, windows, or mechanical systems. High charges may fund reserves prudently. Lower charges may reflect postponed work, borrowing, or a planned assessment. Buyers should ask which explanation fits the records.
Insurance and amenities affect the bill
The board must insure the building when the declaration, bylaws, or unit-owner vote requires it; insurance premiums can affect the budget. The unit owner separately insures interior improvements, personal property, liability, and other unit-level risks. Disclose the association’s coverage, deductibles, open claims, and known gaps through the managing agent and attorney.
A pool, roof deck, lounge, garage, elevator bank, doorman operation, or large mechanical plant costs money to staff, clean, insure, repair, and replace. Amenities can support a higher charge, but their existence does not prove every dollar is well spent. Show service level and financial condition together.
Three Different Monthly Costs
A special assessment is not a second tax
A special assessment is a board-approved charge for a specific need or shortfall. It may fund façade work, an insurance deductible, emergency repairs, a reserve shortfall, or an operating deficit. It is separate from the recurring common charge, even when collected with the monthly bill.
Ask for the resolution, amount allocated to the unit, payment schedule, purpose, invoices or contracts when available, and whether the seller or buyer pays any unpaid balance at closing. A buyer may negotiate a credit or escrow. The contract and closing statement, not a casual email, should control the allocation.
Property taxes and abatements are separate
A condo owner’s New York City property tax bill is separate from common charges. The NYC co-op and condo abatement is filed by the board or authorized managing agent for the development; eligible unit owners must meet primary-residence and ownership rules. Eligibility can depend on primary residence, ownership, annual filing, and other requirements.
A buyer cannot assume a seller’s benefit transfers unchanged.
Show the current tax bill, the latest abatement or exemption detail, and the building’s filing status. If an abatement is scheduled to end, the buyer needs a scenario for the post-benefit tax. Do not describe a tax abatement as a common-charge discount. It reduces taxes after assessment, while common charges fund the condominium’s shared obligations.
Commercial space and shared amenities need a close read
A mixed-use condominium may allocate expenses among residential, commercial, parking, storage, and other units under special provisions. A residential unit may have an exclusive-use terrace, storage room, or parking right with a separate allocation. Read the declaration and budget together.
A master association may provide a gym, garage, plaza, security system, or waterfront facility. Identify the payee, contract term, escalation language, and termination limits. Buyers care less about labels than the cost, obligation, and usefulness of the service.
Investigate the Budget and the Land
Insurance risk can move the monthly number
Insurance premiums, deductibles, exclusions, and required limits can change a building’s budget. Waterfront exposure, older construction, façade work, commercial occupancy, and prior claims may affect pricing and availability. Appropriate insurance and reserves can be easier to defend than thin reserves and repeated assessments.
Request the certificate of insurance, declarations pages where available, claims history, deductible schedule, and any notices concerning renewal or nonrenewal. The seller should let the board or managing agent answer building-level insurance questions. The seller’s own insurance policy is not evidence of association coverage.
Reserves show whether the charge is sustainable
Review at least the current budget, recent financial statements, reserve balance, bank or loan information supplied in the resale package, recent board notices, and any engineering or capital reports available to a buyer. Focus on façade, roof, windows, elevators, plumbing, heating and cooling, electrical systems, life-safety work, and waterproofing. Compare planned spending with reserve funding and debt service.
A reserve account does not guarantee that no assessment will occur. A report can be old, a project can expand, or insurance can change. Transparent records still distinguish a charge funding a plan from one signaling unresolved pressure.
Ground leases change the analysis
Some properties sit on leased land. A ground lease can create a recurring land obligation, escalation terms, consent requirements, financing conditions, and renewal risks. If the property is leasehold, the ground lease may impose rent and other obligations. Whether owners pay through common charges, separately, or another mechanism is document-specific. Do not infer the answer from a listing sheet.
Have counsel review the ground lease, amendments, rent schedule, lender provisions, and expiration or renewal mechanics. A buyer’s lender may treat leasehold differently from fee ownership. Remaining term, escalations, or consent requirements can affect resale.
A Verified FiDi Condominium Example
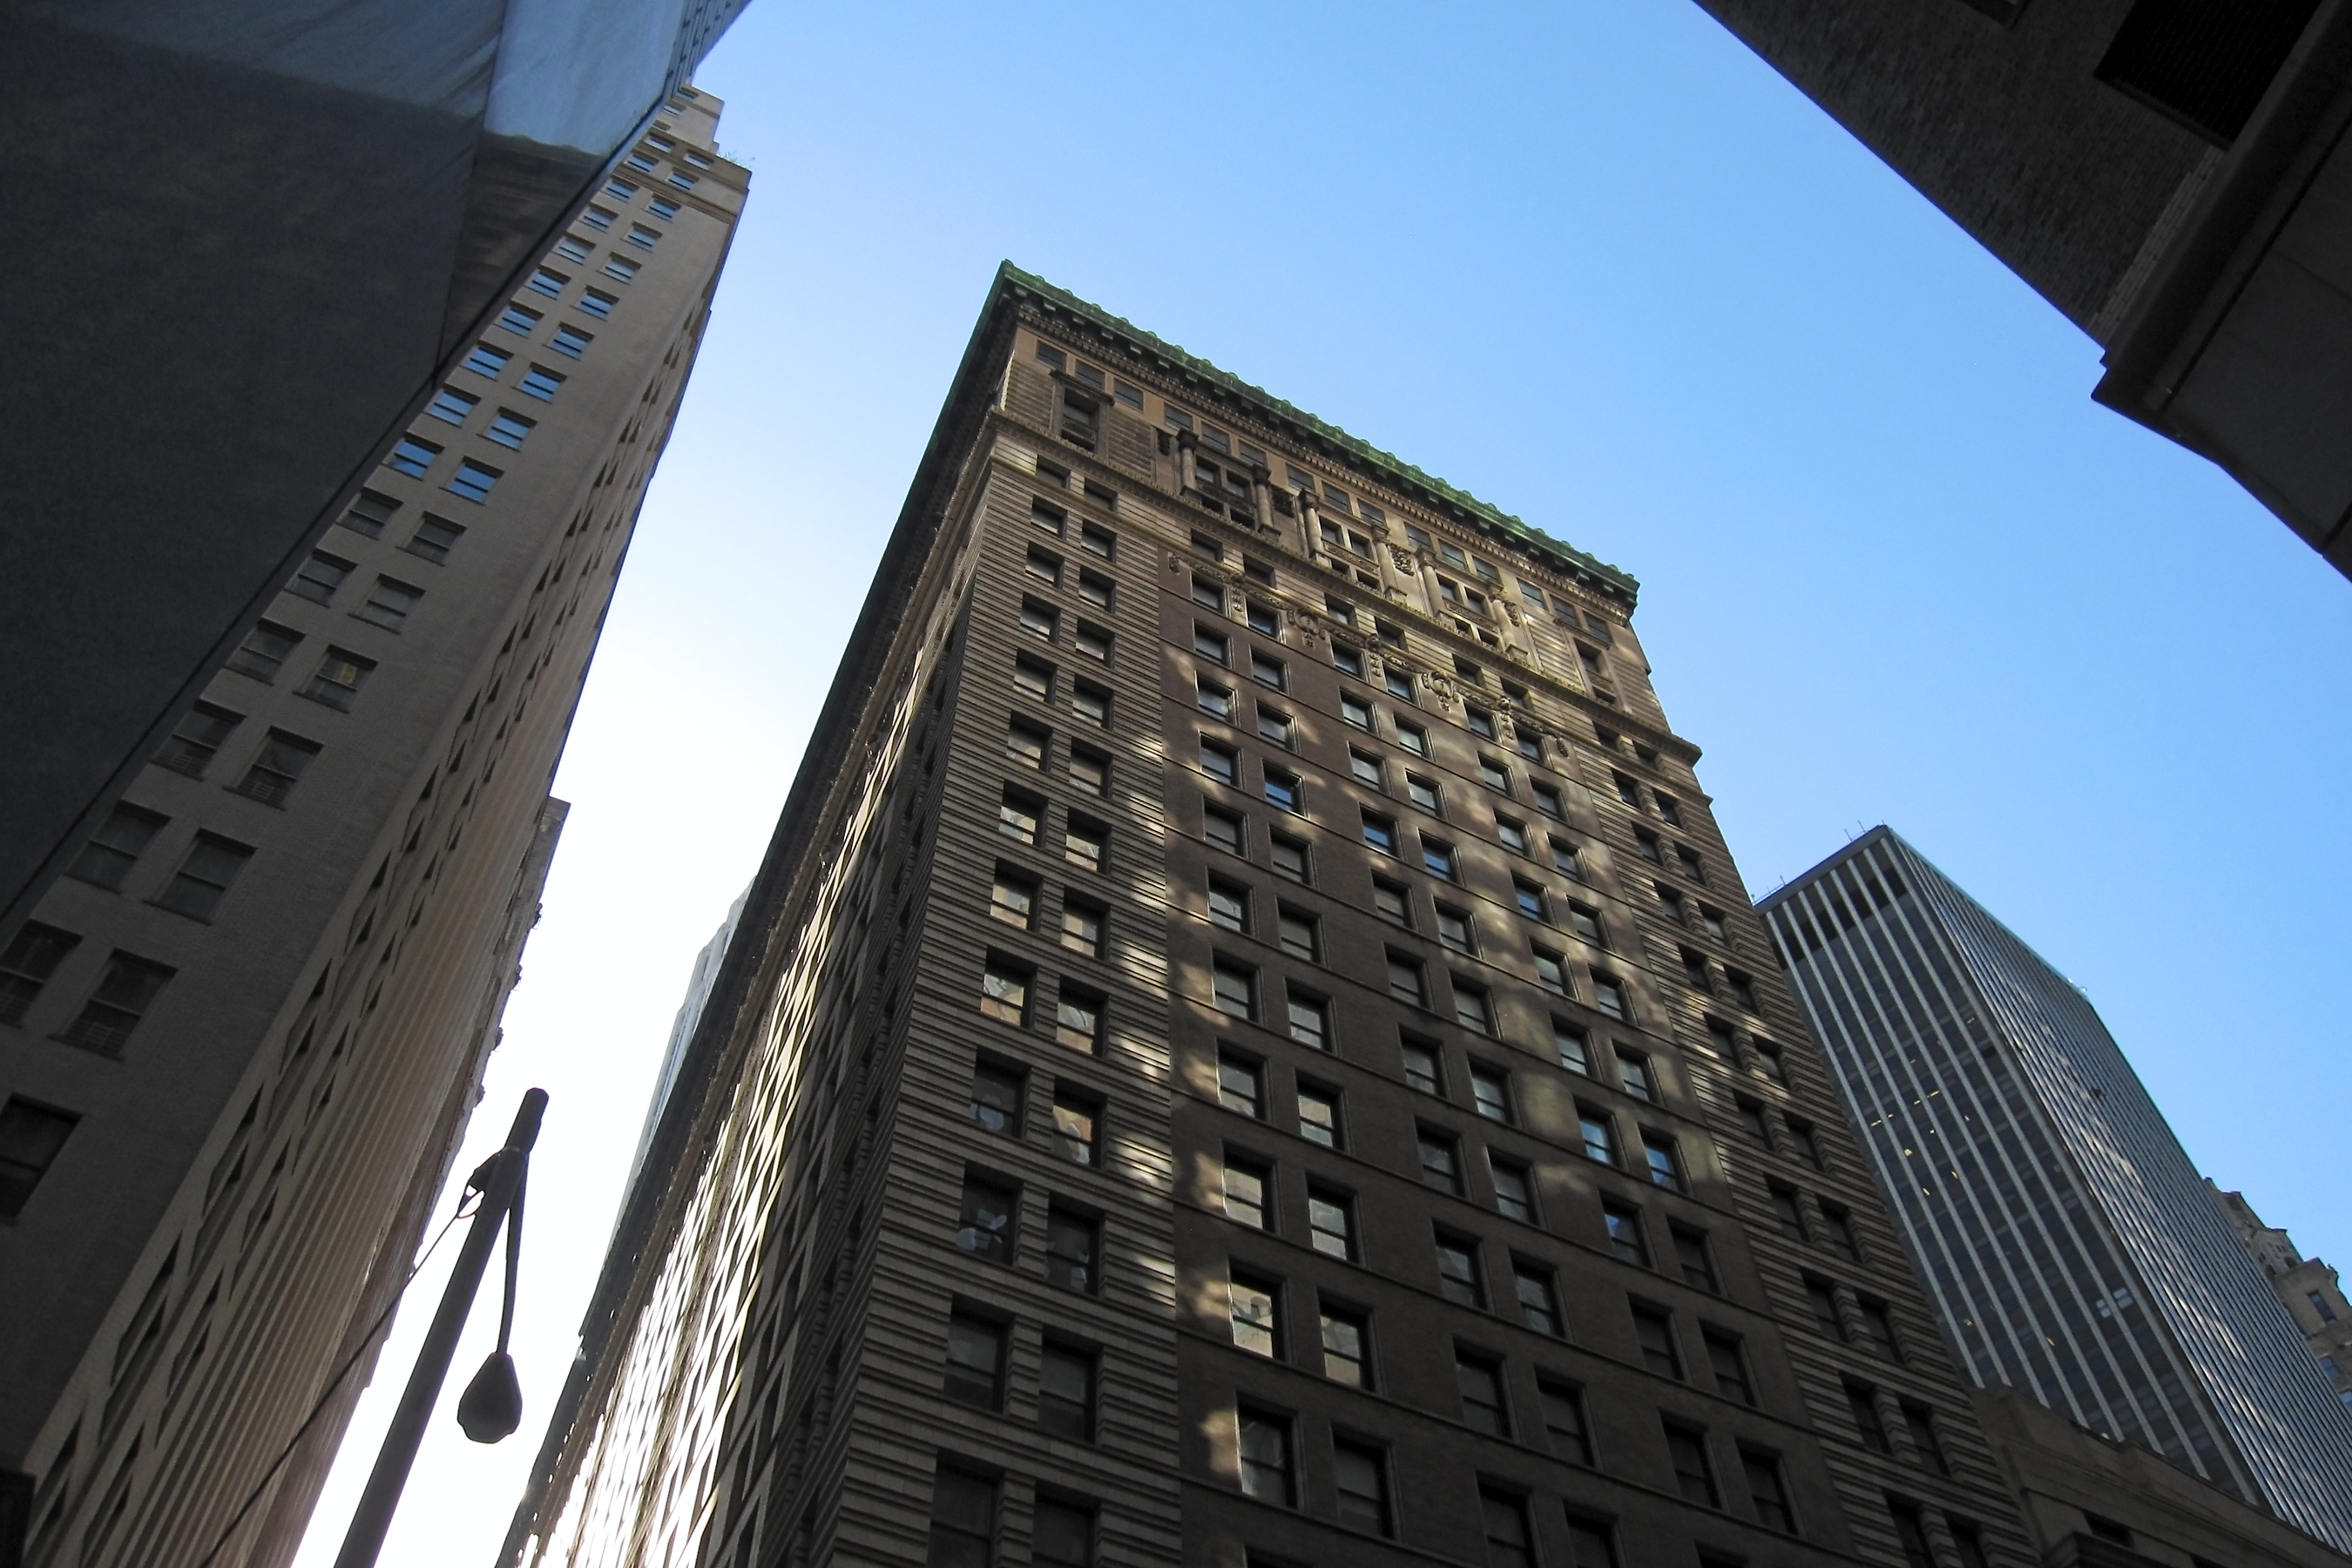
The Broad Exchange Building at 25 Broad Street
The effective NYAG record for The Broad Exchange Building Condominium at 25 Broad Street, Plan CD180154, identifies 308 residences and 283 storage units. It became effective June 22, 2020. That record verifies filing identity, not current charges, commercial ownership, or reserves.
A named building shows why documents and unit-level facts matter. It is not permission to repeat an unverified monthly amount. Confirm the current charge, tax, assessment, abatement, amenities, and financial package from the managing agent and attorney.
Price the Monthly Trade-off With Real Comps
Start with same-building evidence
The best first comparable is a recent closed sale in the same condominium with a similar line, floor, exposure, view, layout, size, condition, outdoor space, storage, and parking rights. Then compare active competition, sponsor inventory, and nearby buildings a buyer would tour. Recorded data verifies that a sale occurred, not its full comparability.
Do not average unlike units into false precision. A renovated high-floor corner and an interior lower-floor apartment can share a bedroom count while competing for different buyers. Explain adjustments and show how charges, taxes, assessments, and abatements affect the comparison.
Convert the charge into a buyer decision
Use a monthly carrying-cost grid with asking price, common charges, property taxes after any verified benefit, and any assessment. Add insurance and financing only for a full budget comparison. The objective is to show the recurring obligation a buyer evaluates.
Consider this hypothetical comparison. Your unit has common charges of $2,400 per month, taxes of $1,100, and a $300 monthly assessment installment. A competing unit has charges of $1,900, taxes of $900, and no assessment. The difference is $1,000 monthly or $12,000 yearly.
If those amounts, including the $300 assessment, continue unchanged for 60 months, the nominal difference is $60,000 before financing. Model the actual assessment term if it ends earlier. That math does not automatically mean a $60,000 price reduction. The higher-cost unit may be larger, renovated, better exposed, or supported by stronger services and reserves. The price and marketing must make the trade-off understandable.
Avoid unsupported neighborhood premiums
FiDi location, transportation, waterfront access, historic architecture, restaurants, schools, and neighborhood growth provide context. They do not erase a building’s recurring cost. Current 2026 pricing should be anchored to verifiable closed sales and current competition, then adjusted for the unit and the building’s monthly economics. Do not use a neighborhood statistic as a substitute for a comparative market analysis.
Seller Strategy
Make the financial story easy to underwrite
Before launch, confirm the current charge, each assessment’s date and reason, taxes before and after any verified abatement, assessment allocation, insurance, reserves, commercial or master-association obligations, ground lease terms, and planned capital work. Get the resale package process and turnaround time in writing.
Write the listing so buyers see value before mystery. Describe services, amenity access, utility inclusions, capital work, and reserve discipline only when supported by records. If the charge rose for a documented reason, say what changed. State any documented assessment end date without promising future budgets.
Set two prices internally. The first is the asking price. The second is the minimum net after taxes, brokerage compensation, legal fees, building charges, move-out expenses, payoff, prorations, unpaid charges, and credits. Revisit both when facts change. For a FiDi pricing review, contact TheNewYorkCityBroker.com/contact-me.
Prepare for buyer and lender questions
Give the buyer’s attorney and lender consistent documents. A missing budget, unexplained assessment, stale insurance certificate, or conflicting charge schedule can delay diligence and weaken leverage. If the building has a sponsor, commercial component, ground lease, or recent capital work, flag it early and let counsel describe the legal effect.
Sponsor sale versus resale
The contract changes the cost comparison
A sponsor sale may shift transfer taxes, sponsor legal fees, working-capital contributions, or other offering-plan charges to the buyer. A normal resale usually presents a different allocation, but the contract controls. Buyers compare the all-in cost of sponsor inventory with the price, condition, monthly charges, taxes, incentives, and closing obligations of your resale.
Ask whether unsold sponsor units remain, whether sponsor concessions are still available, and whether the offering plan or amendments describe projected charges that differ from today’s budget. Do not call a resale cheaper or a sponsor deal more expensive without comparing the actual contract terms.
Build a defensible seller net
Taxes belong in the net sheet
For a hypothetical $1,800,000 individual residential condo resale, NYC RPTT at 1.425% is $25,650. NYS base transfer tax at 0.4% is $7,200, for $32,850 combined before exceptions or contract allocation. The price is below the $2 million supplemental and $3 million additional-base tax thresholds.
The New York State 1% mansion tax is generally a buyer tax on residential consideration of $1 million or more. At $2 million or more in New York City, additional state taxes may apply, and at $3 million or more an additional base tax applies. Confirm with counsel because taxable consideration, property type, and contract terms matter.
Add brokerage compensation, seller attorney fee, managing-agent charges, move-out costs, loan payoff, lien releases, prorations, assessment adjustments, and buyer credits. In the $1,800,000 illustration, hypothetical 5% brokerage and $4,000 legal cost produce a preliminary net of $1,673,150 before loan payoff and other adjustments. This is not a quote.
Protect the closing timeline
Order the payoff early, resolve unpaid common charges, confirm assessment treatment, and ask counsel to identify any transfer contribution or building-specific fee. The board or managing agent may require a questionnaire, waiver, application, move-out reservation, insurance certificate, or resale disclosure. A complete package protects the price because fewer unknowns give a buyer fewer reasons to retrade.
What Fannie Mae review means for your sale
Project eligibility can affect financed demand
For a loan intended for Fannie Mae delivery, the lender reviews the project as well as the borrower and apartment under the applicable path. Fannie Mae’s project standards address project type, insurance, reserves, critical repairs, deferred maintenance, special assessments, and other eligibility questions. The lender may need a questionnaire, budget, financial statements, insurance evidence, engineering material, or project certification.
Do not promise financeability because a prior buyer obtained a loan. A new lender reviews current facts and its own underwriting path. An assessment does not automatically end financing, but its purpose, funding, and project condition matter. Fannie Mae guidance warns that assessments cannot simply replace required reserve funding in a full review.
A seller can reduce delay by authorizing the managing agent to complete the lender questionnaire promptly and by giving counsel a consistent explanation of assessments and capital work. If a project has a known issue, disclose it accurately rather than hoping it will be discovered late.
Closing perspective
High common charges are not automatically a defect. They are a recurring price of shared services, insurance, reserves, staffing, land obligations, commercial complexity, or a capital plan. They become a selling problem when a buyer cannot tell what they cover, whether they are sustainable, what taxes are separate, or what assessment may follow.
The strongest FiDi sale presents verified documents, a building-specific comparable analysis, a transparent monthly-cost comparison, and a seller net that reflects the actual contract. It also separates facts from projections. For selling a FiDi condo with high common charges, or another NYC sale, contact TheNewYorkCityBroker.com/contact-me.
Frequently Asked Questions
No. A higher charge can reflect valuable staffing, utilities, insurance, reserves, amenities, or a larger unit allocation. The pricing question is whether buyers receive value and whether the budget appears sustainable compared with similar buildings. Compare your unit’s total monthly cost with same-building sales and realistic competing listings.
If the difference is material, either price it into the offer strategy or explain the service, condition, space, views, and financial strength that justify it. Keep the explanation consistent in the listing, offering materials, and negotiations. Buyers reward clarity when the charge is easy to verify.
Usually, no. Condo common charges fund shared condominium expenses, while the unit owner generally receives a separate city property tax bill. An eligible owner may receive a cooperative and condominium property tax abatement, but the building or managing agent applies for the development and eligibility can depend on primary residence and other facts.
Show buyers the current tax bill and verified abatement status separately from the common-charge statement. If the benefit could change, explain the documented eligibility condition and timing. Never use an old tax figure as a guaranteed future bill.
The contract should say. The seller may owe installments due before closing, while the buyer may accept future installments, receive a credit, or require the assessment to be paid in full. Do not rely on an informal allocation. Provide the board resolution, purpose, unit allocation, payment schedule, and outstanding balance so attorneys can state the treatment clearly.
A special assessment is a building charge, not a city property tax. Let the attorneys document the allocation in the contract and closing adjustments. The managing agent’s ledger should support the closing figures.
They can contribute to lender concern, but the monthly amount alone is not an automatic denial. The lender may review project reserves, insurance, critical repairs, deferred maintenance, special assessments, commercial elements, and other project standards. A well-documented budget can help. The seller should not promise approval. The buyer’s lender must review current project information under its own underwriting process.
Early delivery of complete documents gives the lender a better chance to identify issues before contract deadlines.
Compare total recurring cost, not common charges alone. Put the asking or sale price, common charges, property taxes, verified abatements, assessment installments, services, amenities, unit size, condition, floor, exposure, and views into the same analysis. A lower-charge building may offer fewer services or weaker reserves. A higher-charge building may offer better staffing or capital funding.
Use closed sales for value and active listings for the buyer’s current alternatives. Recheck the comparison when a competing unit changes price or receives an accepted offer. Market evidence changes during a listing.
Disclose that the property is leasehold and have counsel explain the ground lease’s rent, escalations, remaining term, renewal rights, consent requirements, lender provisions, and how the obligation reaches the unit owner. The cost may appear in common charges, separately, or through multiple governing documents. Do not estimate the effect from a listing sheet.
Buyers and lenders need the recorded documents and current payment obligations before they can assess value. Have the disclosure reviewed by the seller’s New York real estate attorney. That review can prevent an avoidable contract dispute.