Use up and down arrow keys to resize the meta box pane.
Selling an Inherited Manhattan Apartment starts with a question buyers rarely see in the listing: who can legally sign the contract? The answer depends on whether the apartment was a co-op or condo, how it was titled, and whether a court-appointed representative, surviving owner, or trustee controls the sale. Get that answer before choosing a list price. Otherwise, a good offer can sit while an attorney untangles ownership, building paperwork, or a tax release.
Selling an Inherited Manhattan Apartment Starts With Ownership
Read the Deed or Co-op Stock Record First
For a condo, obtain the recorded deed and see exactly how the owners held title. For a co-op, ask the managing agent for the stock certificate, proprietary lease, and transfer requirements. A condo is deeded real property; a co-op sale transfers shares in a corporation together with the proprietary lease. Those differences affect which documents transfer, how liens are cleared, and what the buyer’s lender will request.
Do not assume that two names on a record give the survivor the entire apartment. A joint tenancy with survivorship, a tenancy by the entirety between spouses, and a tenancy in common can produce different results. New York’s ownership rules also address shares and the proprietary lease of a co-op held by spouses. The exact deed or registration, marital status, and any later changes matter more than an informal understanding among relatives.
An apartment placed in a properly funded lifetime trust may be sold by the authorized successor trustee rather than by an estate executor. But a signed trust document does not prove the condo deed or co-op shares were actually transferred into that trust. Ask counsel to compare the trust instrument with the recorded deed or corporation records, then confirm who must sign. For an out-of-state decedent, domicile and possible ancillary proceedings also deserve early review.
Identify the Person Who Can Sell
If a will names an executor, that nomination alone is not a substitute for authority to dispose of estate property. The Surrogate’s Court may admit the will and issue letters testamentary. If there is no will, the court may appoint an administrator and issue letters of administration. If the named executor cannot serve, other forms of appointment can apply. A title company, co-op corporation, or buyer’s attorney will want to see the actual authority and any restrictions.
New York law gives a duly authorized fiduciary broad power to manage and sell estate property, but the will, a specific devise, court order, or limitations in the letters can change the answer. An administrator’s real-property authority may also require closer review. A contested estate can need court direction; an ordinary sale does not automatically require a separate judicial sale order. Have estate counsel settle the signing path before promising a buyer a date.
Probate is not universal, either. The New York Courts explain that, when the only asset is real property and there is no will, a formal administration proceeding may not be necessary in some circumstances. Conversely, a small-estate certificate for a co-op does not automatically authorize selling a deeded condo. The safe rule is to verify the ownership and the accepted closing documents for this particular transaction, not label every inherited sale a probate sale.
Co-op and Condo Buyers Need Different Files
For a Co-op, Work Backward From Board Approval
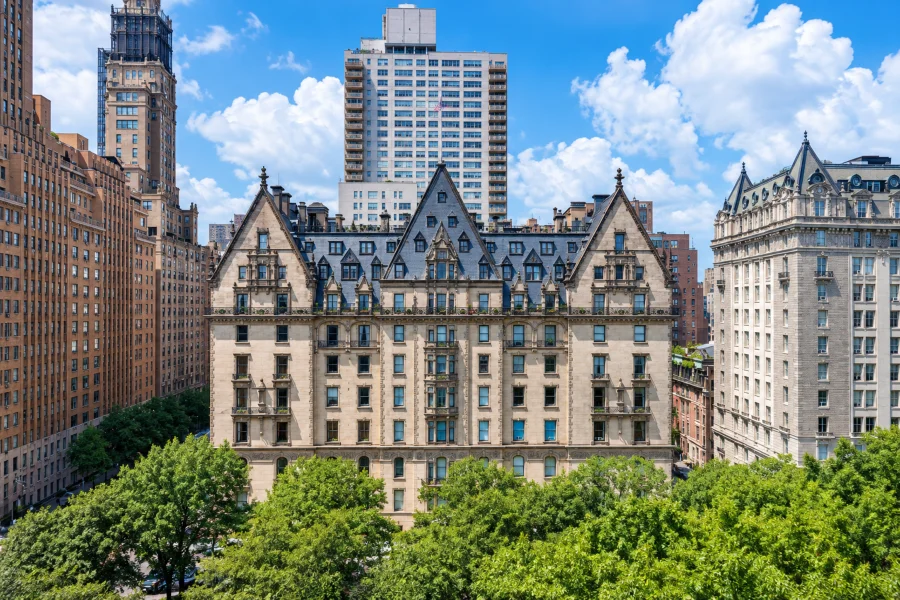
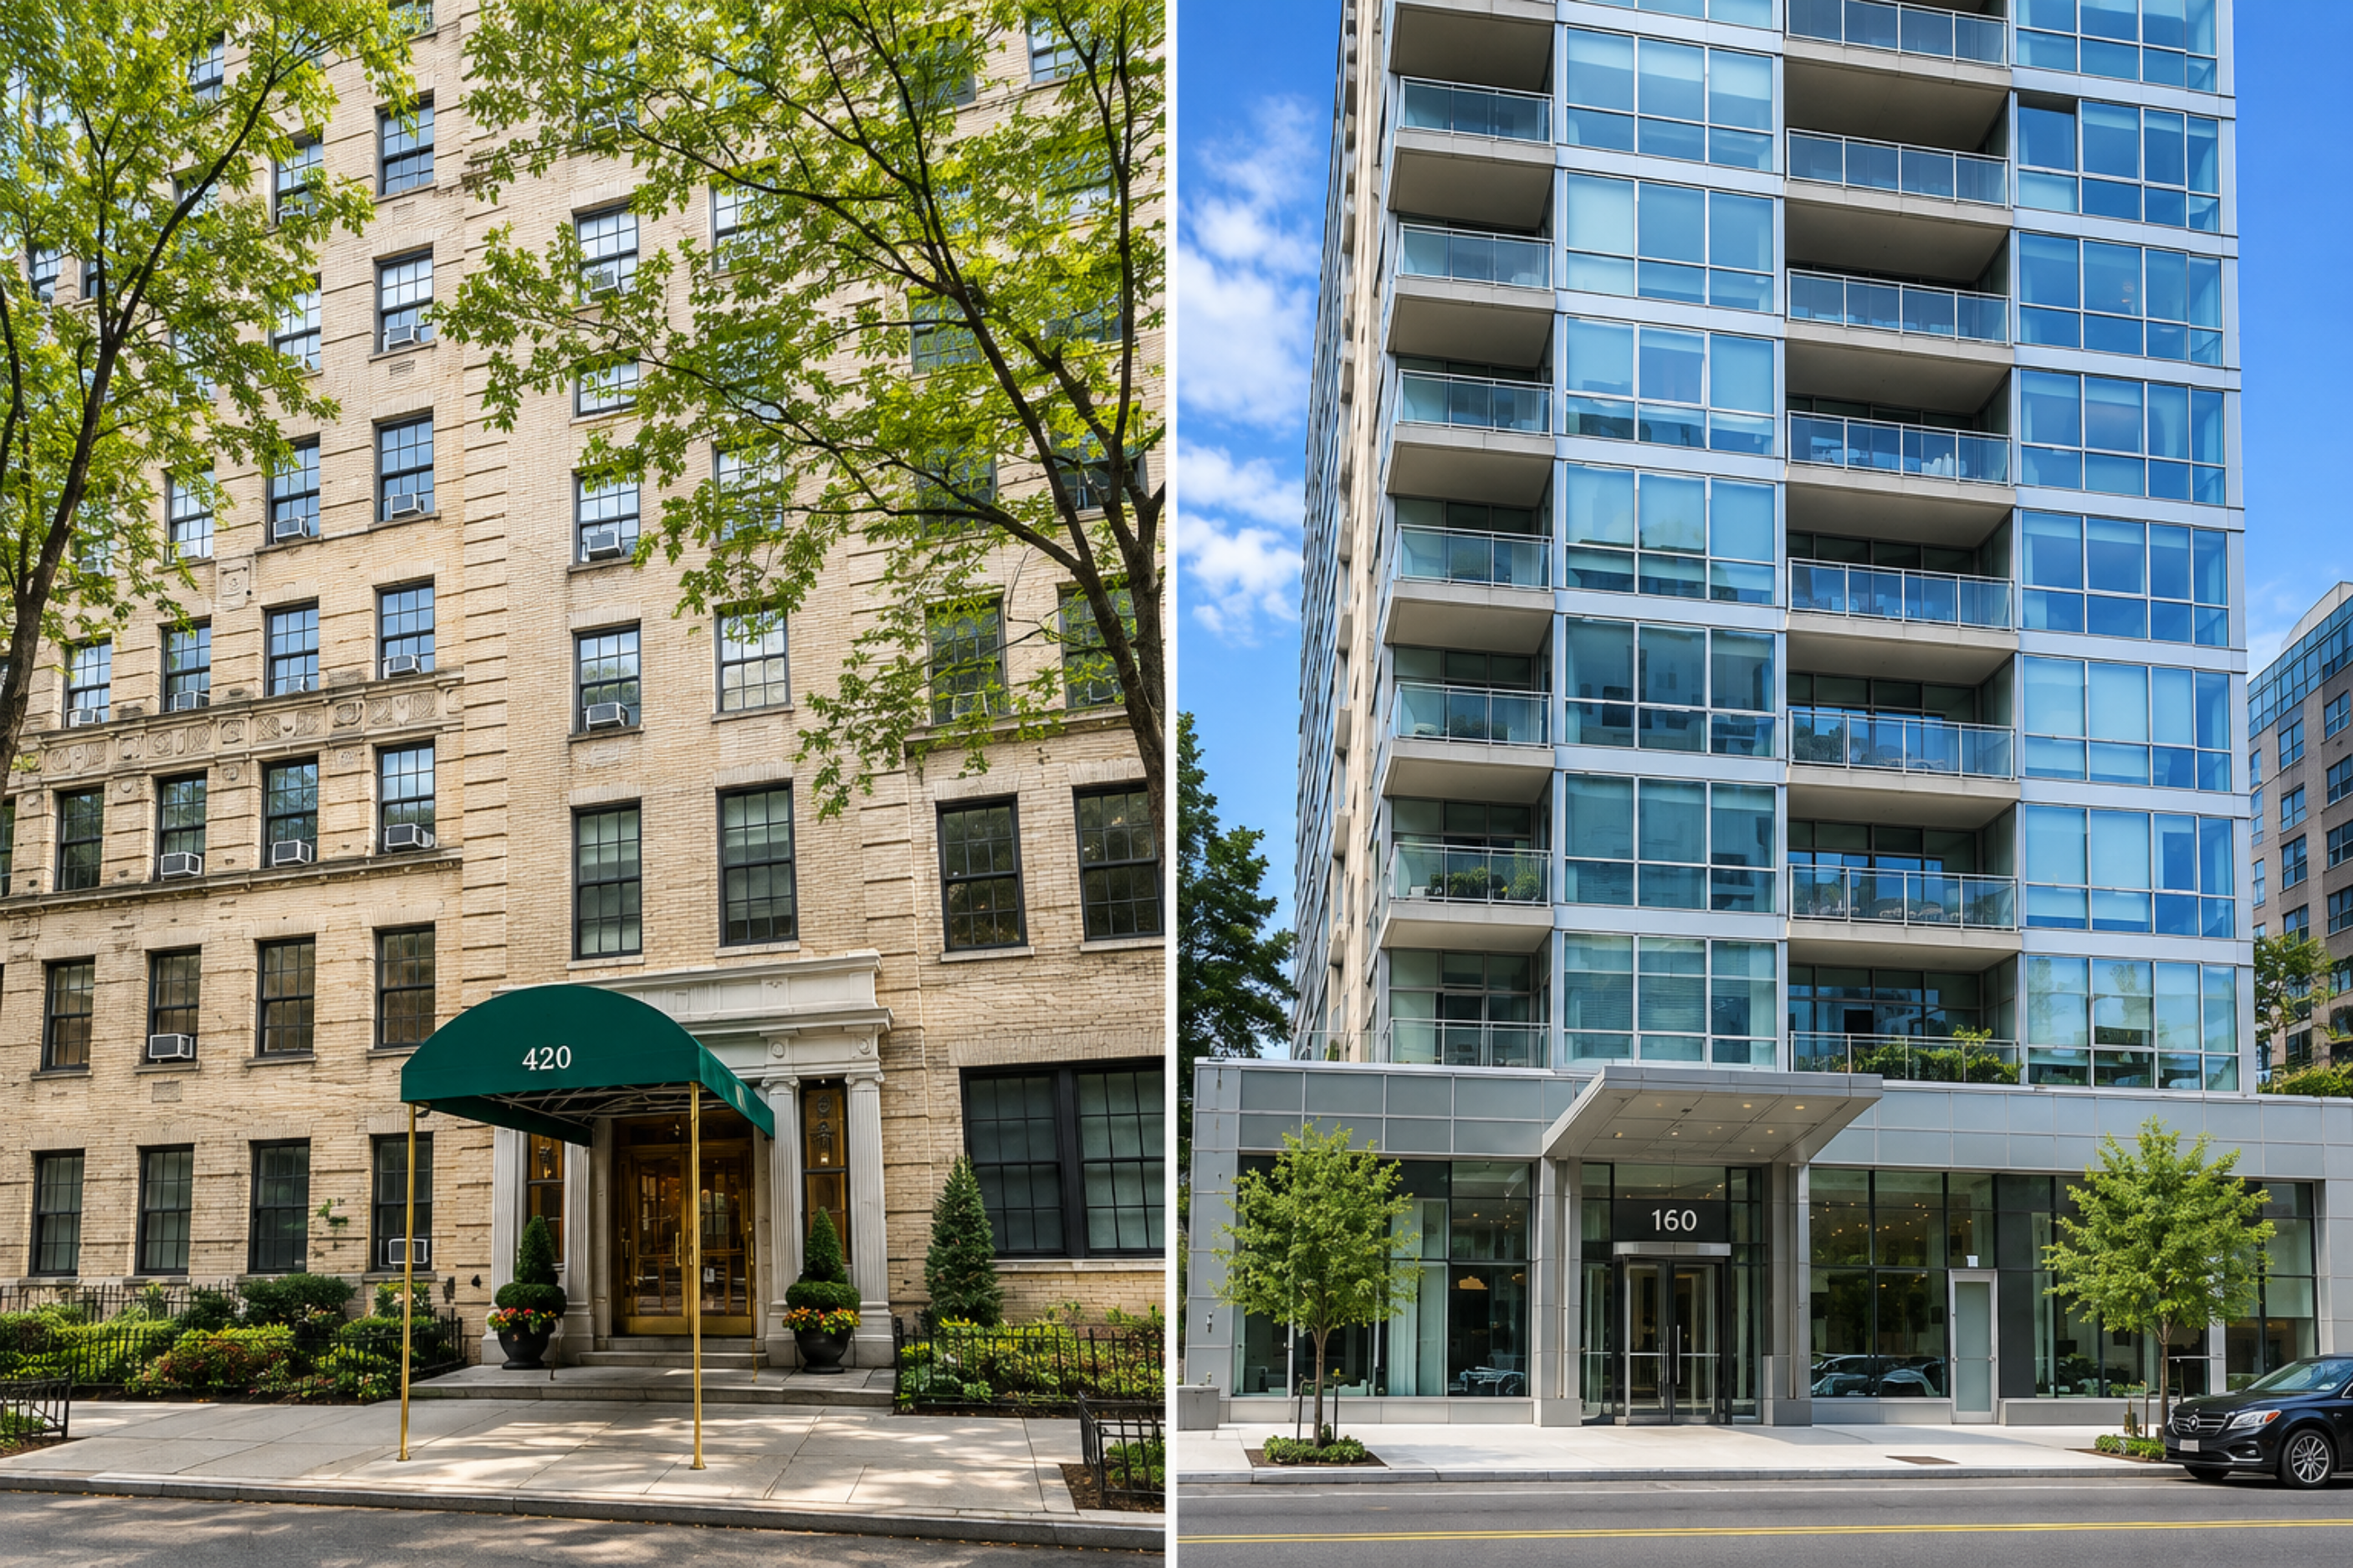
In a co-op such as 1120 Park Avenue, the seller transfers a stock-and-lease interest, not a deed to an apartment. That building is an example of the property type, not an assertion about its current board policy. Obtain the governing documents and estate-transfer package from the managing agent. Check how the corporation recognizes a deceased shareholder’s representative, who signs the contract and stock transfer, whether the proposed purchaser needs board approval, and whether there is a flip tax or transfer fee.
Request maintenance and assessment balances, the original stock certificate, the proprietary lease, any lost-certificate procedure, and the lender’s instructions for releasing a pledged stock certificate. Ask how long the application takes, but do not guarantee a board decision by a specific date. A buyer will care less about the family’s internal timetable than about receiving a complete package and a realistic route to approval.
For a Condo, Prepare a Transferable Deed
At a condominium such as 130 William, the deed, title report, recorded declaration, bylaws, mortgage payoff, taxes, and common-charge status drive the closing file. The project’s official site confirms 130 William is a condominium, but no building-specific sale rule is assumed here. Check whether the declaration calls for a right-of-first-refusal waiver, notice, or other transfer step. A condominium board’s procedure is not the same as a co-op board interview.
New York condominium law allows a lien for unpaid common charges, so get a written statement early. Review assessments, title exceptions, judgments, renovation permits, open violations where relevant, and any mortgage or home-equity line. The estate’s legal authority and the building’s transfer procedure are parallel tracks. Having letters without a waiver, or a waiver without clear title, does not make the unit ready to close.
Price the Apartment From Evidence, Not the Inheritance
Establish Date-of-Death Value Separately From Today’s Ask
For income-tax purposes, inherited property generally starts with fair market value at the date of death, not what the deceased owner paid decades earlier. An alternate estate-tax valuation or other exception may change that basis. Commission a defensible retrospective appraisal when the estate or tax preparer needs one, and keep the appraiser’s assumptions, comparable sales, and supporting documents. The basis valuation answers a tax question; today’s list price answers a market question.
Suppose an apartment has an inherited adjusted basis of $1,800,000 and later sells for $2,000,000. If qualifying seller expenses that reduce the amount realized total $100,000, the illustrative long-term gain is $100,000: $2,000,000 minus $100,000 minus $1,800,000. That is not a tax bill. The actual result depends on the seller’s status, allowable adjustments, depreciation, prior improvements, reporting requirements, and applicable federal and New York rates.
Who sells matters. If the estate closes before distribution, the estate generally handles the income-tax reporting; if a beneficiary receives the apartment and then sells, that beneficiary reports the sale. The tax preparer should match the date-of-death value to any estate-tax filing or Schedule A of Form 8971, where required. A joint owner may have a basis adjustment only on the decedent’s includible share rather than a full reset for the apartment.
Compare As-Is and Light Preparation
Walk the apartment before making an improvement budget. Separate low-cost work that helps buyers see the space, such as removing belongings, cleaning, minor repairs, and accurate photography, from renovations requiring board consent, permits, or months of carrying costs. An estate-condition co-op can attract a buyer who prefers to renovate, but the asking price must leave room for credible work costs. “As-is” is not a substitute for accurate answers about known conditions.
Use the nearest relevant closed sales first. Then adjust for floor, exposure, layout, renovation level, monthly costs, outdoor space, and whether the comparable was a co-op or condo. A high asking price cannot fix an unresolved stock certificate or an expired fiduciary document. Price and documentation work together: buyers tend to negotiate hardest when they cannot tell whether a transaction can be completed on time.
For a practical value and seller-net plan for an inherited Manhattan apartment, reach Brett at TheNewYorkCityBroker.com/contact-me before choosing between as-is pricing and work before listing.
Calculate the Seller Net and Tax Obligations
Separate Estate Tax, Gain on Sale, and Transfer Taxes
These are three different calculations. Estate tax, if any, concerns the decedent’s estate at death. Income tax concerns gain recognized when the apartment is sold after death. Transfer tax concerns the conveyance itself. The 2026 New York estate-tax basic exclusion is $7,350,000 for a person who dies in 2026; that number applies to the broader estate calculation, not to a tax-free sale price for the apartment. The federal estate-tax exclusion and its filing rules are different again.
A beneficiary does not automatically get the federal home-sale exclusion merely because the deceased owner lived there. The seller must satisfy the applicable ownership-and-use requirements or a specific exception. Inherited property is generally treated as long-term for capital-gain holding-period purposes, even when sold soon after inheritance. A gain may still be taxable. Have the estate accountant explain which return reports it and whether the seller is a New York resident, nonresident, estate, or trust.
Nonresident sellers can face a New York estimated income-tax payment at closing or transfer, with exemptions in appropriate cases. For a deeded condo, the form is generally IT-2663; for co-op shares with their proprietary lease, generally IT-2664. It is an estimated payment credited against the eventual income-tax return, not another transfer tax. Verify the tax year and seller identity before anyone prepares the wrong form.
Use a Real $2 Million Closing Example
On a hypothetical sale of one qualifying Manhattan residential condo or co-op for exactly $2,000,000, with no exemption or special consideration adjustment, the seller-side transfer taxes ordinarily include $28,500 of NYC real property transfer tax at 1.425% and $8,000 of New York State base transfer tax at 0.4%. That is $36,500 before negotiated broker compensation, legal fees, building fees, prorations, or a co-op flip tax. A deed from an executor to an outside buyer is not automatically exempt because it is an estate sale.
The buyer’s separate New York State mansion tax at 1% is $20,000. The New York State supplemental tax on a New York City residential conveyance begins at $2,000,000; at that price its 0.25% rate produces $5,000. No extra New York State residential base tax applies at this example price because its threshold begins at $3,000,000. Counsel should calculate the final forms from the actual contract, taxable consideration, seller costs, and any unusual allocation.
An estate representative should also arrange for a New York estate-tax lien release early. Form ET-117 addresses real property and cooperative apartments, with different instructions for each. A tax filing threshold and a lien-release requirement are not the same question. The release is often needed even when a family believes the estate owes no estate tax. Confirm exceptions, paperwork, and processing time with counsel and the New York Tax Department before setting a firm closing date.
Build a Buyer-Ready Estate File
Remove the Predictable Closing Delays
Start with the death certificate, deed or stock certificate, proprietary lease if applicable, will, trust instrument, court letters or other transfer authority, photo identification of signers, and the attorney’s explanation of who conveys the property. Add mortgage or co-op share-loan payoff, common charges or maintenance statement, assessments, tax records, estate-tax lien-release plan, any title or UCC search, and an inventory of apartment access items.
Before a contract goes out, review how to prepare for a Manhattan co-op or condo closing to see the different deed, stock-certificate, payoff, and building-document paths.
Seller Strategy: Choose the Right Route to Market
Make three decisions in sequence. First, confirm authority: determine whether the seller is an appointed executor, administrator, trustee, surviving owner, or beneficiary who has already received title. Second, set a pricing range from recent comparable closings and the actual apartment condition. Third, calculate a seller net at the launch ask, likely contract price, and minimum acceptable outcome. Include transfer taxes, negotiated commissions, legal fees, carrying costs, payoff, assessments, building charges, and any repair budget.
If several heirs disagree, do not use a public listing to settle the argument. Have estate counsel establish who has authority, what the will or ownership record requires, and whether any approvals or court advice are appropriate. For a co-op, ask the managing agent for the transfer package and board timeline before selecting a launch week. For a condo, order title work and the estate-tax lien release before promising a buyer a quick deed closing.
Market the apartment’s verifiable strengths without pretending every estate apartment needs renovation. Show a clear floor plan, accurate condition, recent building sales, realistic monthly costs, and a defined delivery condition. An as-is listing can work when it is priced to the scope of work and the buyer can inspect it properly. Limited preparation can work when it improves presentation without swallowing the proceeds in construction and carrying costs.
Choose the offer that can actually close at a sensible net. Compare the headline price with financing, co-op board readiness, appraisal exposure, requested credits, contract conditions, and the buyer’s understanding of the estate timeline. A buyer willing to provide a complete application and accept a realistic authority-and-release schedule may be stronger than one offering more while expecting documents the estate cannot yet deliver.
Finish With a Closing Plan, Not a Guess
If you are selling an inherited Manhattan apartment or another New York City property, contact Brett through TheNewYorkCityBroker.com/contact-me to build a price and closing plan around the actual ownership documents.
Frequently Asked Questions
No, probate is not required for every inherited Manhattan apartment. The route depends on how the deceased owned the condo or co-op and who has legal authority now. A valid survivorship interest may pass directly to a surviving owner, and an apartment properly titled in a lifetime trust may be sold by its authorized trustee. A sole owner’s will may need probate and letters testamentary; no will may call for administration. New York Courts also note that a real-property-only intestate estate may not always require administration. Counsel should check the deed or stock-and-lease record.
Generally, a person merely named as executor should not promise to convey an estate apartment before the necessary court authority is issued. The will identifies a proposed executor; the Surrogate’s Court admits it to probate and issues letters testamentary, or preliminary letters where appropriate. The exact letters, will provisions, co-fiduciary signatures, and any limits on sale power matter. If the apartment is specifically devised, held in trust, or subject to a court restriction, the answer can differ. Estate counsel should establish the signing authority before contract. An expected appointment is not completed authority.
Yes. A co-op sale transfers the apartment corporation’s shares and the related proprietary lease; a condo sale conveys a deeded unit. In a co-op, obtain the stock certificate, proprietary lease, building transfer package, board requirements, maintenance statement, and share-loan payoff if applicable. In a condo, confirm the deed, title exceptions, mortgage payoff, common-charge and assessment statement, declaration, and any right-of-first-refusal waiver. Both may need proof of estate or trust authority and New York estate-tax lien-release paperwork. Neither property type has one universal building approval timeline.
Not necessarily, but selling soon does not make the transaction automatically tax-free. The inherited basis is generally fair market value on the date of death, subject to alternate-valuation and other rules. Taxable gain is measured against that adjusted basis after considering allowable selling expenses and improvements. A quick sale near an accurately appraised date-of-death value may produce little gain, while a higher price, a partial basis adjustment, or depreciation can change the result. Inherited property is generally treated as long-term for federal holding-period purposes. The deceased owner’s occupancy does not automatically give an heir the home-sale exclusion.
The seller ordinarily pays NYC real property transfer tax and the New York State base transfer tax on an arm’s-length sale, whether the seller is an estate, trustee, or heir. On a qualifying single residential co-op or condo sold for $2 million, the unadjusted examples are $28,500 of NYC tax and $8,000 of state base tax. The buyer ordinarily pays mansion tax and, at that price, the state supplemental tax on an NYC residential conveyance. Contract terms can change the economic allocation. An executor’s deed given as part of a sale is not automatically exempt from NYC tax.
Start with the death certificate, deed or co-op stock certificate and proprietary lease, will or trust, letters or other proof of signing authority, and any required co-fiduciary consents. Then obtain mortgage or share-loan payoff, title or lien information, maintenance or common-charge balance, assessments, estate-tax lien-release plan, building transfer rules, renovation records, and a date-of-death valuation for tax review. The estate’s accountant should determine whether the estate or an heir reports the sale and whether a nonresident estimated-tax form applies. Document the apartment’s condition and what will be removed before closing.