Selling a FiDi condo against sponsor inventory means competing with more than a developer’s asking price. The sponsor may offer transfer-tax credits, free common charges, staged presentation, preferred financing, or a price amendment while protecting the published value of the remaining units. A resale seller has a different advantage: operating history, known monthly costs, completed improvements, and a conventional resale cost allocation.
The right strategy compares the buyer’s total cash, monthly obligation, apartment condition, financing risk, and closing timeline. A sponsor unit with the same headline price may cost more or less after taxes and incentives. The seller should map the actual choices, price from closed evidence, and set the minimum acceptable net before negotiation begins.
Why Sponsor Inventory Changes FiDi Resale Math
Sponsor Inventory Is Live Competition
FiDi buyers can tour new sponsor units and established resales in the same week. Sponsor apartments may offer unused finishes, amenity access, warranties, immediate occupancy, and professionally staged common areas. Resales may offer customized interiors, window treatments, storage, established views, completed punch-list work, or lower buyer closing exposure.
Neither category wins automatically. A sponsor contract can be less flexible on financing or allocate more costs to the buyer. A resale may need renovation, carry an assessment, or face an appraisal based on recent sales. The comparison should use apartments serving the same buyer, not every unit in a large building or neighborhood.
Asking Price Is Not Effective Price
A sponsor can preserve headline pricing while offering tax credits or months of common charges. A resale seller may reduce price instead, include furniture, give a closing credit, or accept a preferred date. Convert every concession into dollars and confirm whether the lender, appraiser, contract, and tax calculation recognize it the same way.
Separate asking price, effective buyer cash, monthly carrying cost, expected renovation, and likely resale timing. An unclosed sponsor ask is active competition, not a comparable sale. A recorded sponsor transfer can also reflect contract terms or stipulated values that require review before it is used as a valuation point.
Map the Inventory a Buyer Actually Sees
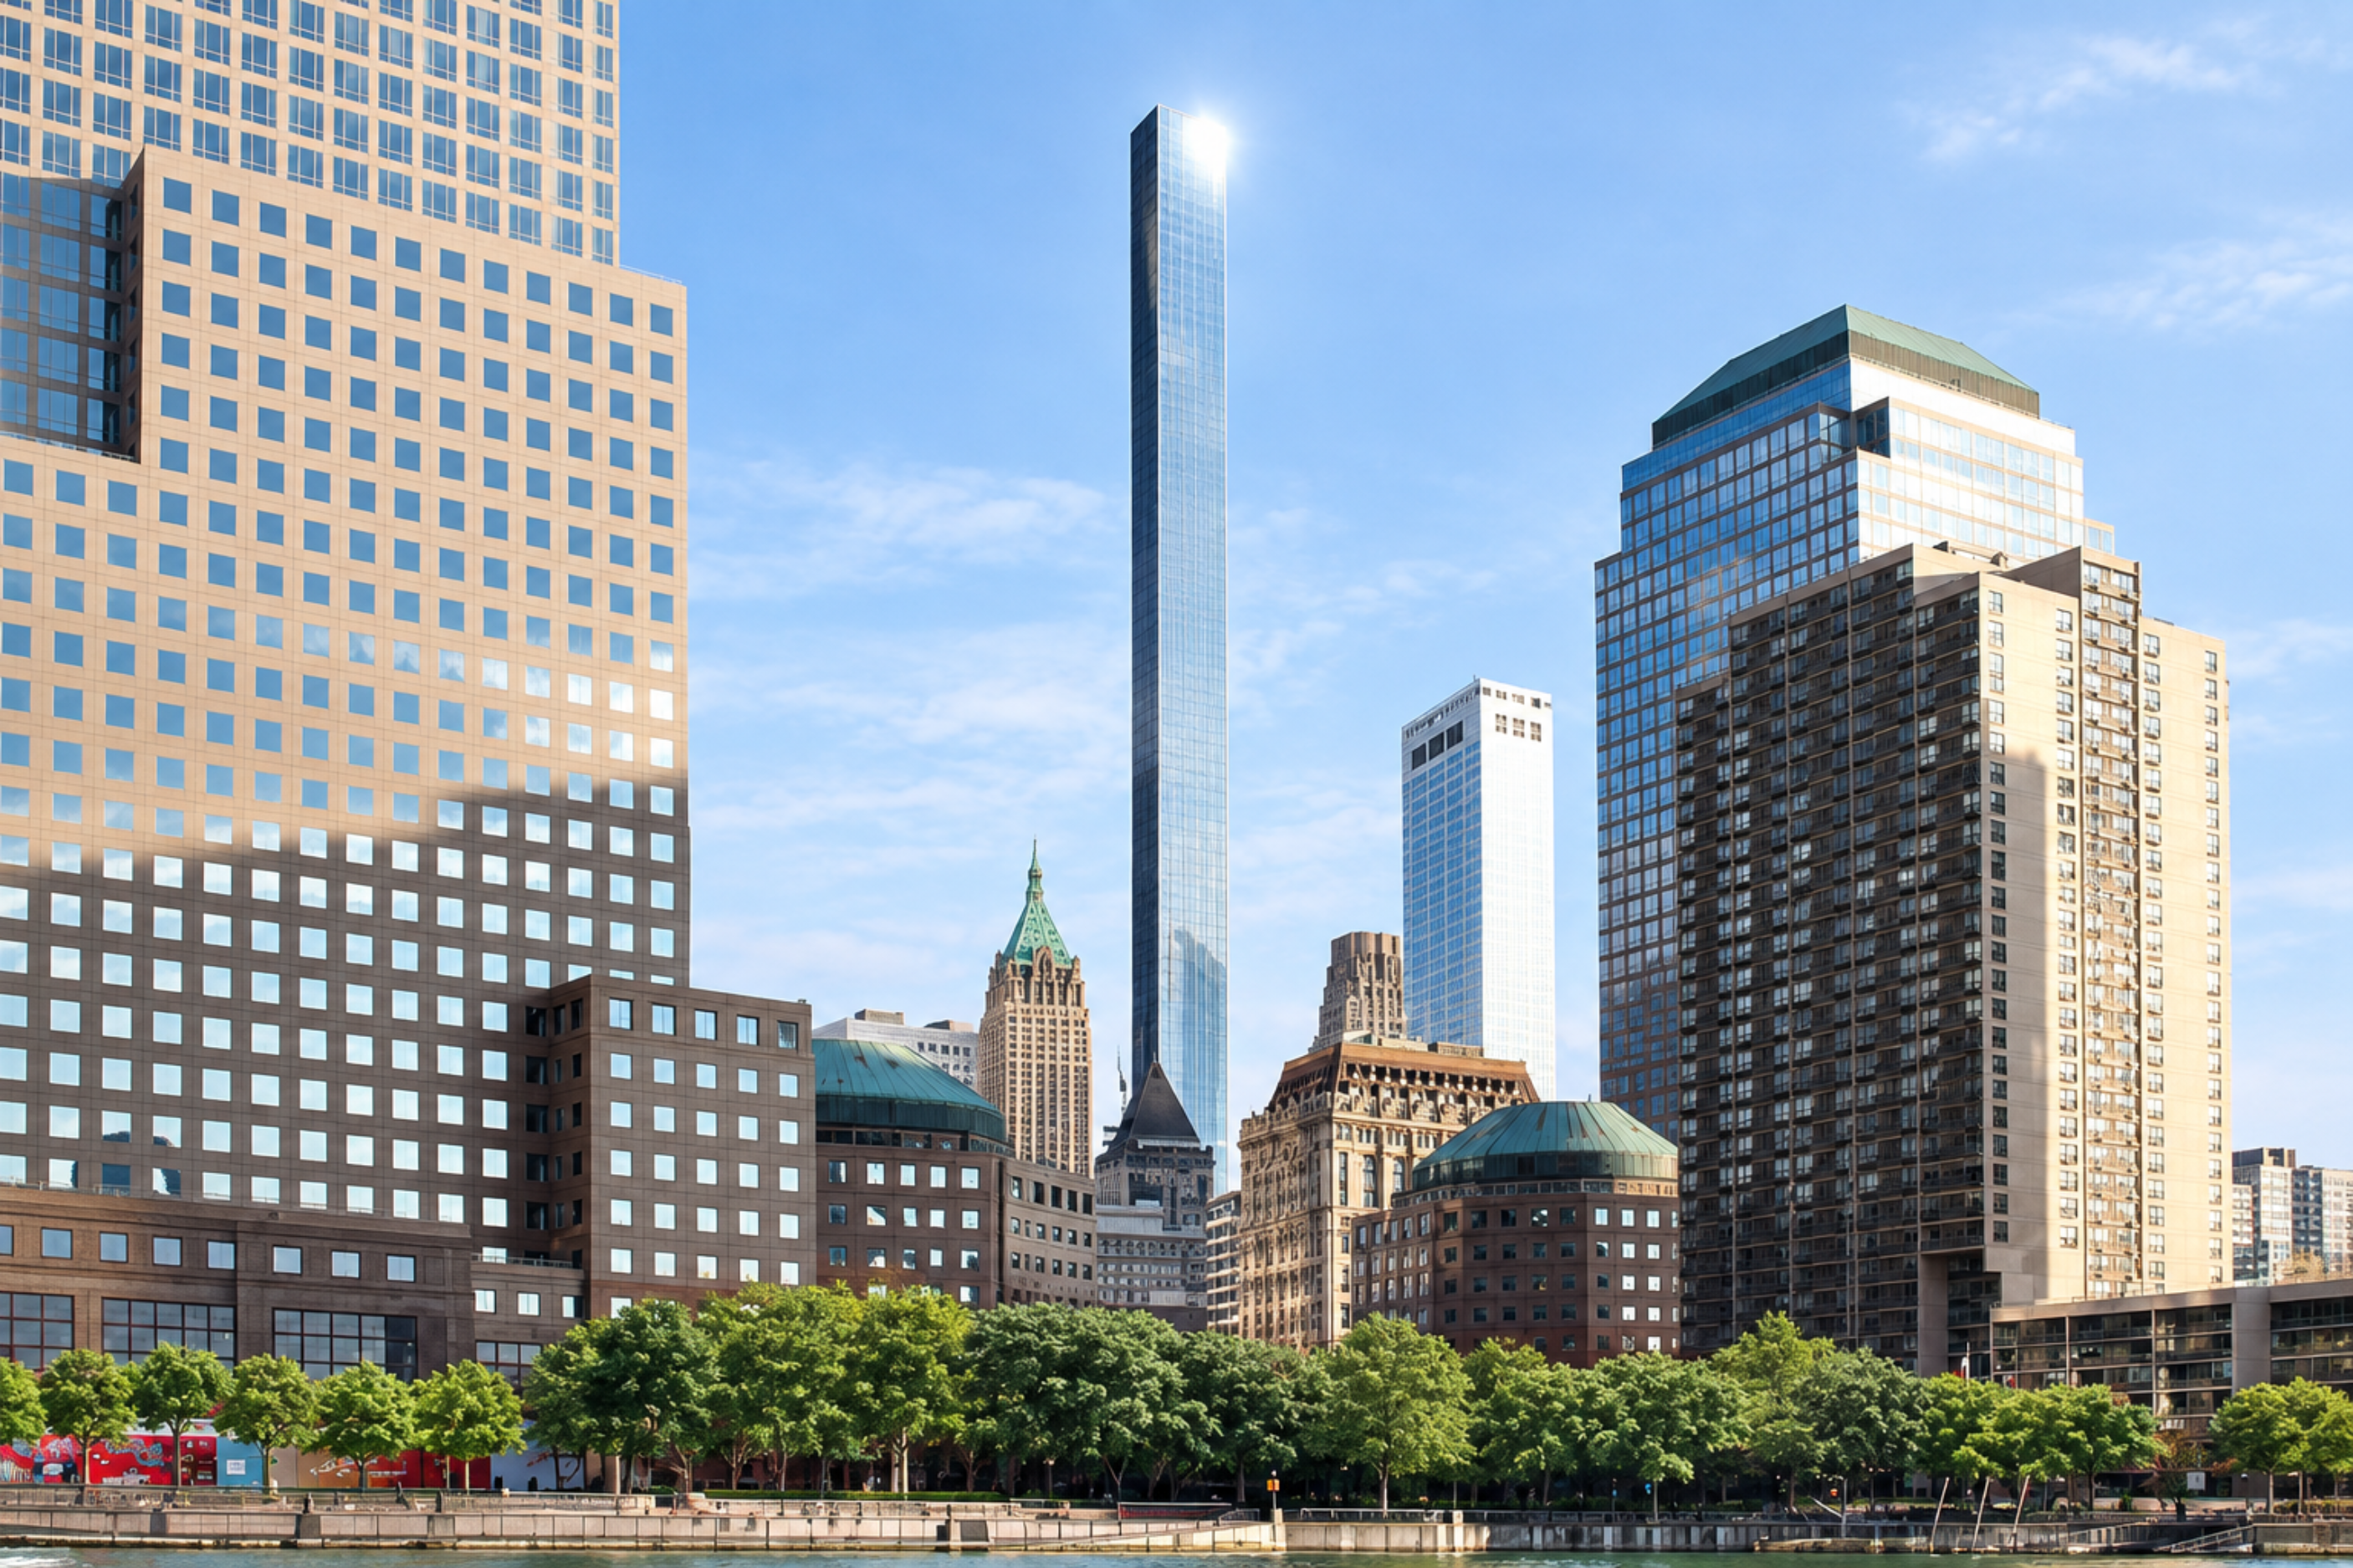
One Wall Street
One Wall Street’s Attorney General plan, CD170216, lists 566 residences and became effective January 11, 2023. Dated public records showed substantial sponsor inventory in 2025 and 2026. Unit 2308 was listed at $2.995 million in November 2025, and Unit 2413 was listed at $1.975 million in June 2025. A sponsor Unit 1211 sold for $2.3 million in January 2025 after a $2.5 million last ask.
Resale Unit 816 was asking $1.825 million in June 2026 after a prior $1.973717 million closing in 2023. Building-level marketing in 2025 reported sponsor-paid transfer taxes and 12 months of free common charges for availability, but that does not prove every contract received the same package. A resale seller must compare against the exact sponsor unit and current written incentive.
130 William
Plan CD180040 lists 244 residences and became effective December 4, 2019. Sponsor Unit 50A was listed at $6.64599 million in July 2025, reduced to $6.25 million in May 2026, and entered contract at that ask. Sponsor Unit 52D was asking $3.875 million in February 2026, while PH65 was asking $18 million in April 2026.
Resales were visible beside that inventory. Unit L56B was asking $4.399999 million in April 2026 after a $4.25606 million 2021 closing. Unit 50B was asking $1.995 million after an April 2026 reduction and had previously closed at $1.913843 million. Compare size, loggia, floor, exposure, upgrades, and seller status before treating these figures as direct alternatives.
125 Greenwich and 77 Greenwich
The 125 Greenwich plan, CD150336, lists 275 residences and became effective April 3, 2025. Its amendment history records repeated 2025 and 2026 price changes. Unit 79B was asking $2.5 million in March 2026, and reported sponsor closings in 2026 included Unit 66B at $2 million and Unit 51A at $1.605 million. The amendment history matters more than the original launch sheet.
At 77 Greenwich, plan CD180179 lists 90 residences and became effective June 17, 2021. Dated 2026 sponsor asks included $2.395 million for Unit 39B and $3.15 million for Unit 38C. Building-level marketing in late 2025 reported six months of common charges and six months of property taxes for availability. Confirm any current incentive in the contract rather than assuming an older program continues.
Price the Buyer’s Total Cash, Not the Asking Price
Model Sponsor and Resale Charges Separately
In a typical resale, the seller generally pays the 0.4% New York State base transfer tax and NYC RPTT of 1.425% for an individual residential condo above $500,000. A sponsor contract may shift those seller obligations to the buyer and may add sponsor counsel, working capital, or other project charges. The contract and offering plan control the allocation.
At a $1.95 million price, nominal seller transfer taxes are $7,800 of NYS tax plus $27,787.50 of NYC RPTT, totaling $35,587.50. The buyer mansion tax is $19,500. Under an illustrative sponsor contract adding $4,000 sponsor counsel and $4,000 working capital, buyer cash is $43,587.50 higher than the same-price resale before any sponsor concession or gross-up.
A resale and sponsor unit at the same ask do not necessarily require the same cash. For the buyer-side arithmetic, review Financial District closing costs before positioning the resale.
Include Monthly Costs and Assessments
Compare common charges, property taxes, assessments, insurance, included services, and any abatement or subsidy. A sponsor credit can reduce first-year expense without changing the recurring charge after the credit ends. A resale can compete with a stable operating history, but current budgets and assessment notices must support that claim.
If the resale carries an assessment, show the monthly amount, duration, purpose, project status, and proposed contract allocation. If the sponsor unit has projected rather than actual operating history, identify that difference without implying the budget is wrong. Buyers respond better to documented costs than vague assurances.
Build the Asking Price From Evidence
Start With Same-Building Closed Sales
Prioritize recent closed sales in the same line, then adjust for floor, exposure, layout, documented size, condition, outdoor space, storage, monthly charges, and seller type. Separate sponsor closings from resales because contract allocations and incentives can affect the recorded economics. Use deed and closing records where possible rather than relying only on listing status.
Add active inventory as competition. A sponsor unit that remains available after reductions can cap buyer urgency, but it does not prove the resale’s value. Compare the exact apartment a buyer can choose today and refresh the sponsor’s Schedule A price, sales-office availability, and incentive before launch.
Use Tax Thresholds Deliberately
The buyer mansion tax is 1% at $1 million or more. A separate NYS supplemental tax applies to qualifying NYC residential conveyances beginning at $2 million. At $1.999 million, buyer mansion tax is $19,990. At exactly $2 million, mansion and supplemental taxes total $25,000, so a $1,000 price increase creates $5,010 more buyer tax.
That cliff can influence search and negotiation, but it should not force a resale worth materially more than $2 million below the threshold. Compare the tax saving with the price surrendered, seller net, and probability of another buyer. If shifted sponsor costs or gross-up language place the economic consideration near a threshold, have the attorneys and title company calculate it from the actual contract.
Prepare the Apartment and Building File
Make the Resale Easy to Compare
Repair obvious defects, improve lighting, declutter, and use an accurate floor plan and strong photography. Document renovations, permits, board approvals, warranties, appliances, storage, and exclusive-use rights. Buyers comparing staged sponsor inventory will discount unclear condition more than a plainly explained resale scope.
Prepare Diligence Before Launch
Gather the declaration, bylaws, offering plan and amendments, current budget, financial statements, insurance, reserve information, assessments, capital work, litigation disclosures, common-charge history, tax bills, waiver requirements, managing-agent contacts, and mortgage payoff estimate. Confirm any right of first refusal and its deadline from the governing documents rather than assuming a universal 30-day period.
Provide an arrears and assessment statement before closing and allocate charges clearly in the contract. A complete file helps the buyer’s attorney and lender assess the project before a rate lock, appraisal, or closing date becomes vulnerable.
Use Financing and Appraisal Evidence as a Resale Advantage
A resale in an operating condominium can be easier for a lender to analyze when the building has current financial statements, established insurance, completed common areas, closed comparables, and a documented reserve and assessment history. That does not guarantee approval. Litigation, critical repairs, insurance gaps, investor concentration, or deferred maintenance can still affect eligibility. Prepare the project file early and identify who completes lender questionnaires.
Recent financed closings are helpful context, not transferable approvals. The new lender still evaluates the buyer, unit, appraisal, title, and current project condition. Give the appraiser relevant same-building sales, documented renovations, floor-plan support, outdoor space, storage, and verified concessions. Do not present sponsor asking prices as closed evidence.
A sponsor unit may face new-project rules or limited comparable history, while a resale may carry a prior purchase price buyers can see. Neither determines value by itself. The seller’s strongest position is a clean apartment and building file showing why the resale’s line, condition, monthly costs, and transaction structure support the ask.
Seller Strategy: Make the Resale Easier to Choose
Build a net sheet at the launch ask, expected contract price, and minimum acceptable outcome. Include NYC RPTT, NYS transfer tax, negotiated brokerage compensation, attorney fees, managing-agent charges, move-out costs, prorations, concessions, private building fees, assessments, and mortgage payoff. Show payoff separately because it reduces proceeds but is not a selling expense.
At a $1.95 million resale, 5% brokerage, ordinary seller transfer taxes, and a $3,000 attorney produce an illustrative net of $1,813,912.50 before payoff, building charges, adjustments, and income taxes. The same gross sponsor price can appear more competitive while shifting $35,587.50 of nominal seller taxes to the buyer. That allocation explains part of the buyer’s comparison but says nothing about the sponsor’s development or carrying costs.
Sell the effective-value difference with records. A resale may offer known common charges, established financials, completed improvements, window treatments, storage, or a faster conventional resale process. State only what the documents support. Do not promise easy financing, a guaranteed waiver, or lower costs for every buyer.
Compare offers by net and certainty. Review financing, appraisal risk, concessions, sale contingencies, target date, waiver process, and building diligence. A slightly lower offer with credible financing and a clean timeline may beat a higher offer that depends on an aggressive appraisal or unresolved project review.
If you are selling a FiDi condo against sponsor inventory, contact Brett to model the resale net, buyer cash requirement, and launch position, then broaden the analysis to any New York City real-estate move.
Launch, Negotiate, and Protect the Net
Track qualified showings, repeat visits, questions, and offer quality during the first two weeks. If buyers consistently cite sponsor incentives, common charges, condition, or closing cash, identify which comparison is driving the objection. Do not reduce price merely because the sponsor has more inventory; determine whether the resale needs a price change, a credit, better documentation, or stronger presentation.
During negotiation, compare the sponsor’s current written terms rather than sales-gallery summaries. A common-charge credit has an expiration and dollar value. Sponsor-paid taxes may be unit-specific. A price amendment can change the appraisal set. Keep an updated effective-price worksheet and recalculate seller net after every counteroffer.
Protect the closing by confirming financing, appraisal timing, title, insurance, waiver requirements, assessment allocation, and the building’s document turnaround. Certainty is valuable only when the buyer, lender, attorneys, and managing agent can support the proposed date.
Selling a FiDi Condo Against Sponsor Inventory: Price the Comparison
Map the sponsor and resale inventory, compare total buyer cash, normalize monthly costs and condition, price from closed evidence, prepare the building file, and set the seller’s net before negotiating. Sponsor competition changes the comparison, but it does not erase the resale’s value when that value is documented clearly.
If you are selling a FiDi condo or planning another New York City real-estate move, contact Brett to compare the offer, concessions, timing, and likely proceeds.
Frequently Asked Questions
Price it from recent same-building and same-line closed sales, then adjust for floor, exposure, layout, size, condition, outdoor space, storage, common charges, taxes, assessments, and seller type. Add active sponsor units as competition, but do not treat their asking prices as closed comparables. Convert every verified sponsor incentive into dollars and compare the buyer’s total cash and monthly cost. Refresh the current Schedule A, sales-office availability, and listing history immediately before launch. Set a launch ask, expected contract range, and minimum acceptable net so negotiation decisions are tied to evidence rather than the sponsor’s original launch pricing.
No. A sponsor unit may have a lower ask, new finishes, warranty coverage, or incentives, but the contract may shift transfer taxes, sponsor counsel, working capital, and other charges to the buyer. A resale may have lower buyer closing exposure, completed improvements, established common charges, and an operating history, but it can also need renovation or carry an assessment. Compare effective buyer cost, monthly obligations, condition, financing, appraisal risk, and timing. Confirm concessions in the written contract because a building-level promotion does not prove that every unit receives the same taxes, credits, or free common charges.
The statutes set default liability, but the contract controls the economic allocation between the parties. NYS base transfer tax and NYC RPTT are generally seller obligations, while mansion and NYS supplemental taxes are generally buyer obligations. Sponsor contracts often require the buyer to bear or reimburse the sponsor’s seller-side taxes and may add sponsor legal or working-capital charges. The attorneys and title company should calculate the final taxable consideration and any NYC RPTT gross-up from the actual documents. A resale seller normally pays the ordinary seller transfer taxes unless the contract or a statutory exception provides otherwise.
Only when comparable sales, expected seller net, and buyer demand support it. At $1.999 million, the buyer mansion tax is $19,990. At $2 million, the buyer owes $20,000 mansion tax plus $5,000 NYS supplemental tax, so the $1,000 price increase adds $5,010 of buyer tax. That cash cliff can affect searches and negotiation, but it should not force an apartment worth materially more below the line. Compare the buyer saving with the price surrendered and probability of another offer. If sponsor-shifted costs may affect consideration, have counsel calculate the threshold from the contract.
Prepare the declaration, bylaws, offering plan and amendments, budget, financial statements, insurance, reserves, assessments, capital-project information, litigation disclosures, common-charge history, property-tax bills, waiver or right-of-first-refusal procedure, and managing-agent contacts. Add renovation approvals, permits, warranties, appliance records, storage documents, accurate floor-plan support, and the mortgage payoff estimate. Ask for an arrears and assessment statement and confirm how declared assessments will be allocated in the contract. A complete package helps the buyer’s attorney, lender, appraiser, and title company evaluate the resale before missing records create delay or undermine confidence.
The closing date depends on the contract, financing, appraisal, title, insurance, building diligence, document delivery, waiver procedure, and the parties’ schedules. There is no universal statutory timeline for a financed condo resale. A target of roughly 60 to 90 days may be used as a planning estimate in some transactions, but it is not a guarantee or legal rule. Confirm the governing documents’ waiver period, lender project review, appraisal timing, managing-agent turnaround, and any assessment or title issue before promising a date. A cash buyer can still be delayed by diligence, title, waiver, document requests, building arrears, or scheduling. Set expectations from the actual contract and building process.