“How much is my apartment actually worth?” It sounds like a simple question, but selling a pre-war co-op on the Upper East Side makes the answer a little more complicated. At 740 Park Avenue, financing has historically been prohibited on most transactions, requiring buyers to purchase with cash. That one detail tells you something important: the building itself can have a major impact on who can buy an apartment and what they are willing to pay.
Two pre-war apartments can look almost identical on paper and still sell for hundreds of thousands of dollars apart. The difference usually comes down to the building, the line, the condition, the maintenance, and how the apartment is positioned against the competition.
The building matters. The line matters. The financials matter. The board process matters. And the buyer pool for your apartment is shaped by all of it.
That is why pricing a pre-war co-op by looking at what sold three blocks away can get you into trouble. A sixth-floor classic six in one building can attract a very different buyer and command a very different price from a similar-sized apartment in another building.
The Upper East Side is still a deep co-op market, but buyers are doing more homework before they make offers. Recent reporting has placed Manhattan co-op median pricing around the mid-$800,000s, while Upper East Side co-ops can vary dramatically depending on building, size, condition, and location.
If you are selling in 2026, the goal is not simply to put the apartment on the market. It is to make the buyer understand exactly why your apartment is worth the number you are asking.
Your Building’s Numbers Set Your Price Before a Buyer Ever Tours
Before deciding on an asking price, look at what your building has actually been trading for.
Start with recent closed sales, not just current listings. An asking price tells you what another seller hopes to receive. A closed sale tells you what a buyer actually agreed to pay.
Then narrow the comparison further.
Look for apartments with a similar bedroom count, approximate square footage, floor, exposures, renovation level, maintenance, and financing structure. A renovated pre-war apartment with low monthly carrying costs should not automatically be compared with an unrenovated unit carrying significantly higher maintenance just because both have two bedrooms.
The building’s financial structure matters, too.
A buyer reviewing your apartment may look closely at maintenance, the underlying mortgage, reserve levels, assessments, financing rules, and recent capital projects. If your building has a major project coming up, that can affect the way buyers calculate their offer even if the apartment itself is beautifully renovated.
This is where buyer psychology comes into play. Buyers rarely think only about the sticker price. They are thinking about the total monthly commitment and the amount of cash they need to keep available after closing.
For example, a buyer looking at a $1.5 million apartment may have the income to qualify, but if the purchase requires a large down payment, closing costs, renovation money, and significant post-closing liquidity, their offer may be lower than the seller expects.
Price gets attention. Carrying costs and liquidity determine whether a buyer can actually act.
The Comparative Market Analysis Has to Be Building-Specific
A useful comparative market analysis, or CMA, should start with your building and then expand outward.
For a pre-war Upper East Side co-op, I would want to see several layers of information:
- Recent closed sales in the same building
- Current competing listings in the building
- Recent sales in comparable nearby buildings
- Price per square foot where the comparison is genuinely useful
- Maintenance and assessment differences
- Floor and exposure
- Renovation quality
- Financing restrictions
- Flip-tax structure
- Time spent on the market
- Whether previous listings had price reductions
Price per square foot can be helpful, but it should not become the entire pricing strategy. Pre-war apartments are rarely identical boxes. A gracious layout, original details, better light, a higher floor, or a particularly good line can create meaningful differences that a simple price-per-square-foot calculation misses.
This is also why a stale listing can be more dangerous than a slightly aggressive initial price. If an apartment sits for months without activity, buyers begin to wonder what is wrong with it, even when nothing is wrong. The market starts to create its own story around the listing.
A well-priced apartment gives buyers a reason to act now instead of waiting for the seller to reduce the price.
For a deeper look at the pricing strategy behind a Manhattan sale, see How Do You Price a Manhattan Apartment to Sell Without Chasing the Market?
What the Flip Tax Actually Costs You
A flip tax is a transfer fee charged by the co-op when an apartment is sold. Depending on the building’s governing documents, it may be paid by the seller, the buyer, or split between the two.
The important point is simple: do not assume the percentage from another Upper East Side building applies to yours.
Current listing information for 1120 Park Avenue and 1185 Park Avenue, for example, has shown a 2 percent flip tax payable by the purchaser. Those are building-specific terms, not a universal Upper East Side rule. The governing documents and current managing-agent information should always control.
That distinction matters when you calculate your net proceeds.
If a building charges a 2 percent flip tax on a $2 million sale and the seller is responsible for it, that is $40,000 before considering any other selling expenses. If the buyer pays it instead, the economic impact can still matter because the buyer may account for that cost when deciding what to offer.
The same principle applies to assessments and other building-specific charges. Before you set your asking price, understand exactly what the seller is expected to pay and what the buyer is expected to pay.
Staging a Pre-War Apartment Is Its Own Discipline
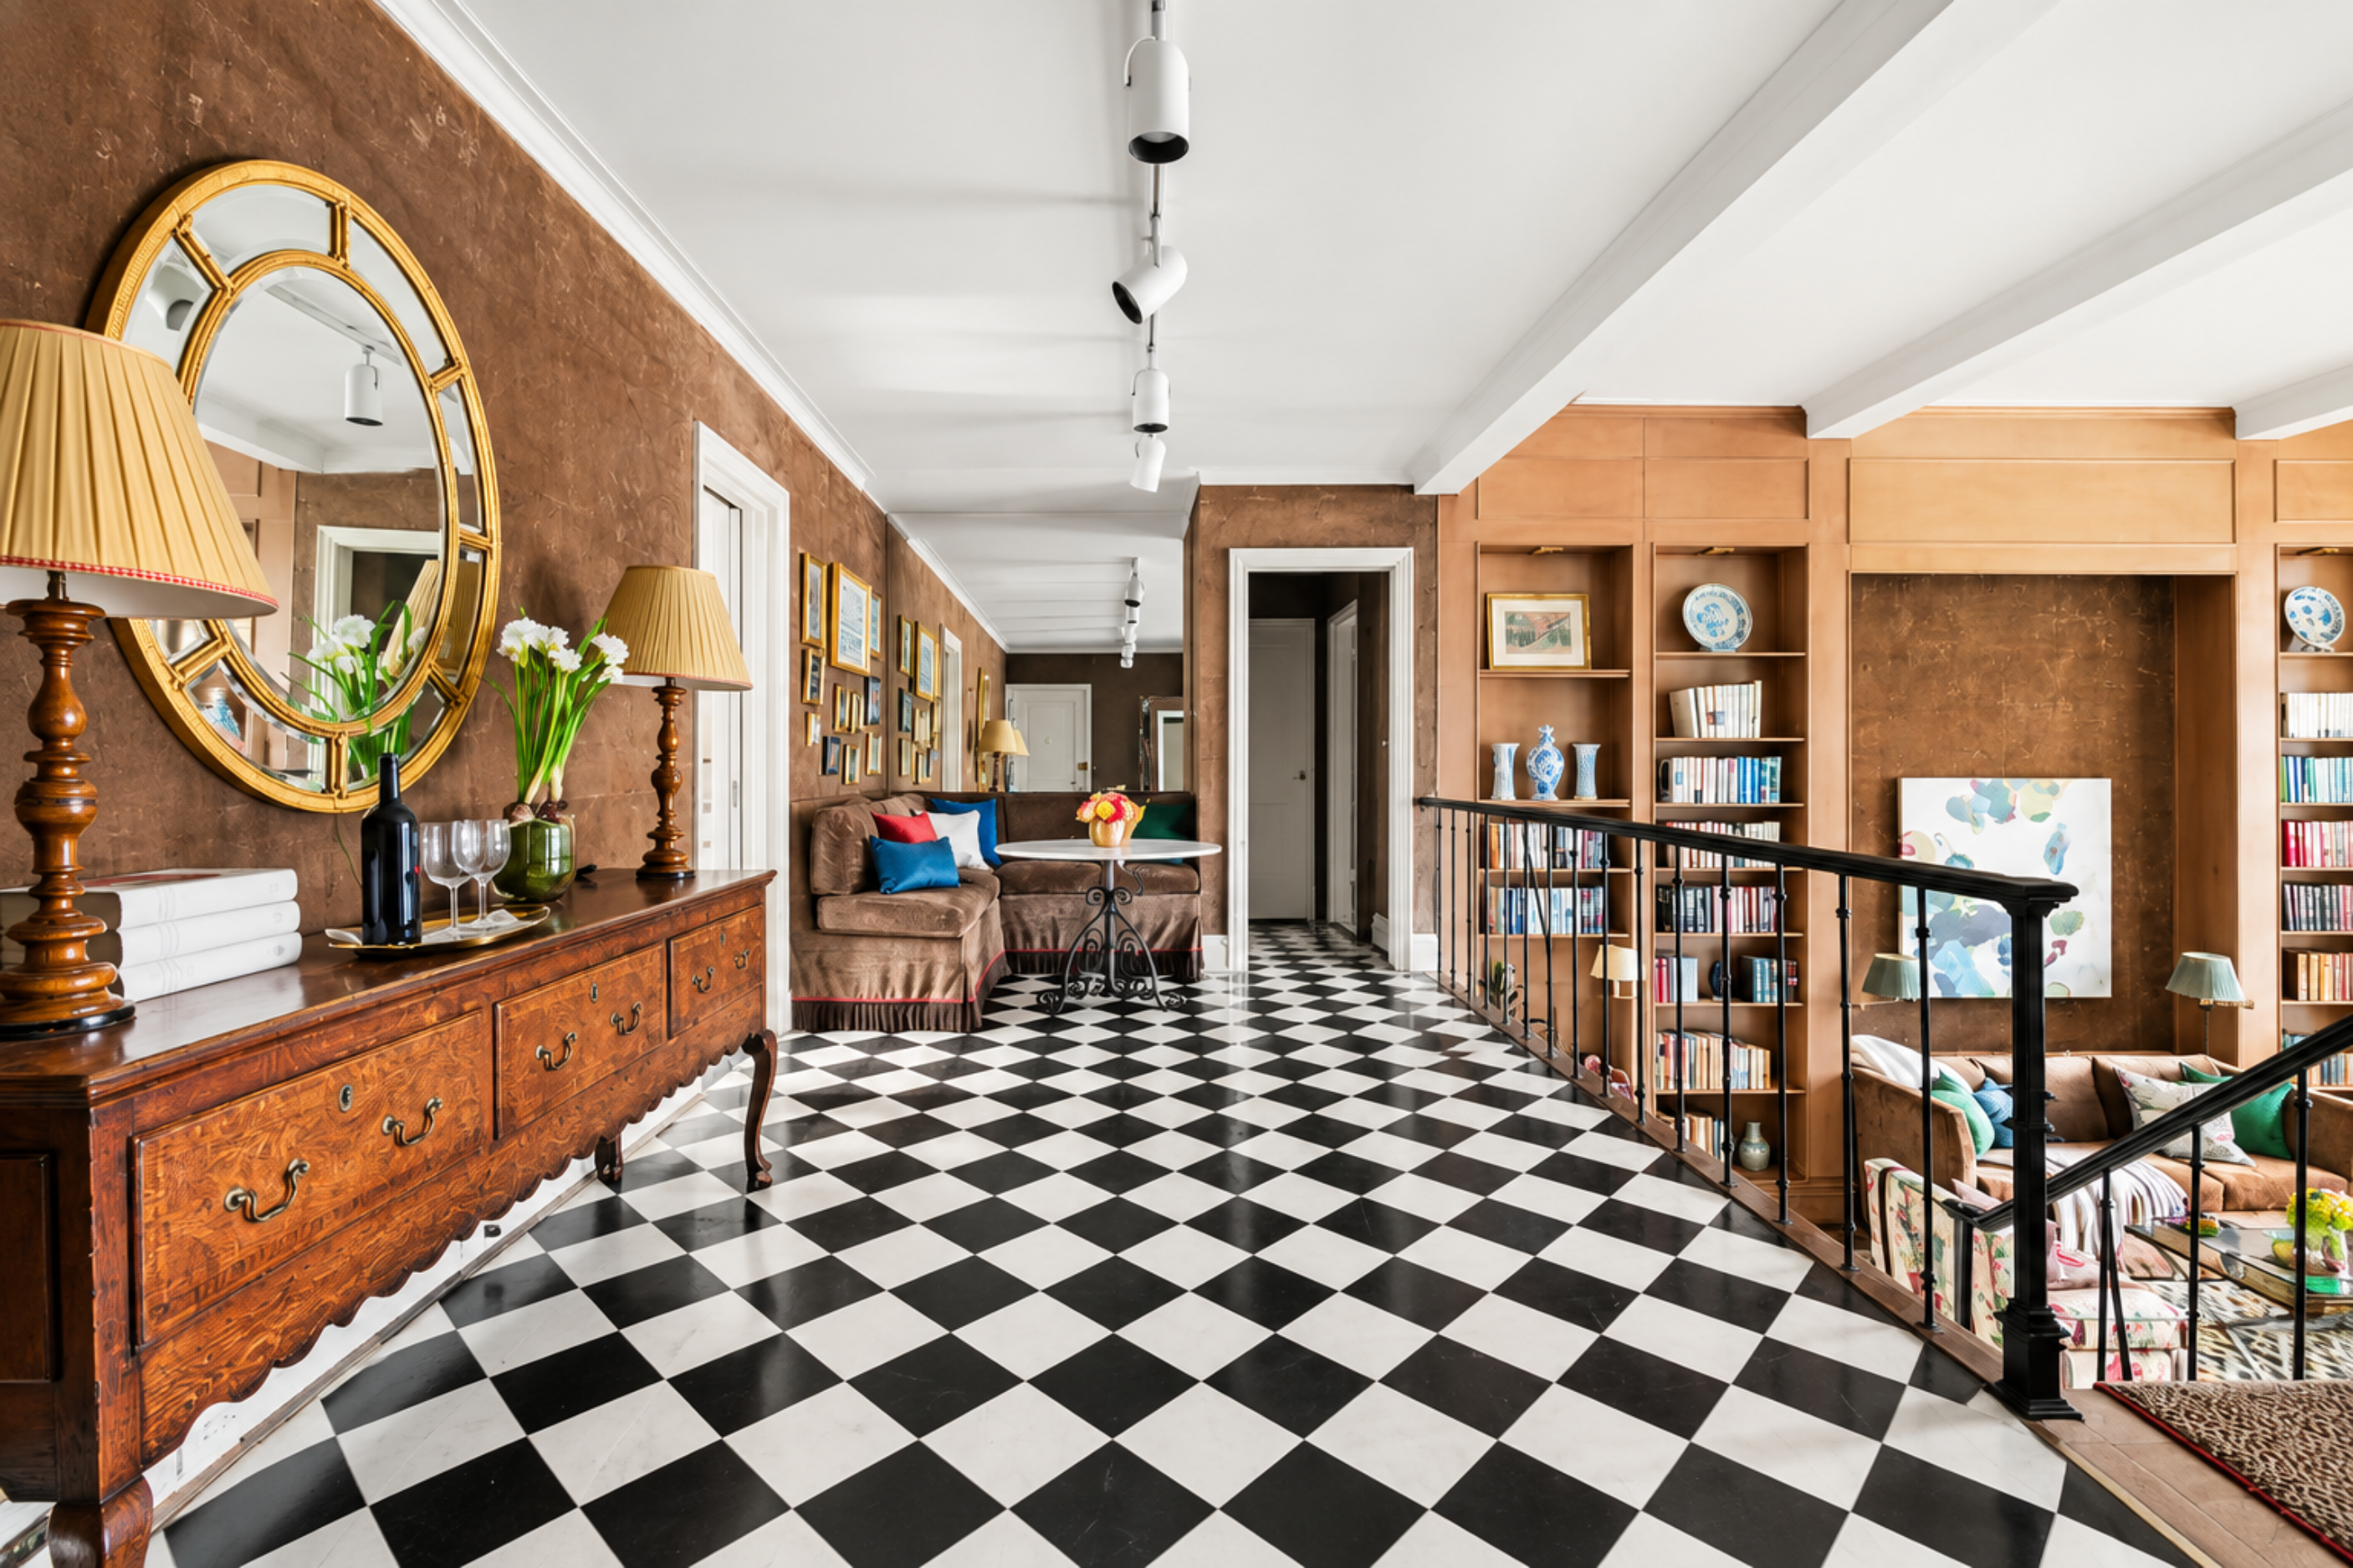
Pre-war apartments usually sell best when buyers can immediately understand the proportions and layout of the space.
That does not mean stripping away every piece of personality. It means making the apartment easy to read.
Remove furniture that blocks circulation. Clear crowded rooms. Repair small cosmetic issues that distract from the apartment’s stronger features. Make sure closets can be opened and viewed. If there are original details worth highlighting, make them visible instead of hiding them behind furniture.
Lighting matters, too. Replace burned-out bulbs, open curtains, clean windows, and make sure rooms photograph the way they actually feel in person.
The goal is not to make a pre-war apartment look like a new-development model unit. The goal is to show buyers what they are buying.
If the apartment has a formal entry, a gracious living room, original moldings, high ceilings, or a particularly strong layout, the presentation should help those features register immediately.
Photography and floor plans matter for the same reason. A buyer may make the first decision about whether to visit your apartment before ever stepping inside.
Get Your Paperwork Ready Before You Go Live
A co-op sale can slow down for reasons that have nothing to do with the apartment.
Before listing, collect the documents a buyer’s attorney and lender are likely to request. That can include the proprietary lease, offering-plan materials where applicable, recent financial statements, building rules, alteration agreements, assessments, maintenance information, and details about any pending capital projects.
If your apartment has undergone renovations, make sure the paperwork matches the work that was actually done.
This matters because a buyer who discovers a documentation issue late in the process may need additional legal review, lender review, or board documentation. Those extra steps can create delays that were avoidable from the beginning.
The same applies to the building itself. If there is an assessment, refinancing, major capital project, or other financial issue buyers will discover during due diligence, it is better to understand it before going to market.
Good preparation does not guarantee a fast sale. It does reduce avoidable surprises.
Qualify Buyers Before You Accept an Offer
The highest offer is not always the strongest offer.
With a co-op, the buyer’s financial profile can matter almost as much as the price because the transaction may ultimately depend on board approval and building-specific financial requirements.
Before accepting an offer, get enough information to understand how the buyer plans to finance the purchase. That can include a mortgage preapproval or proof of funds, the proposed down payment, and other financial information appropriate to the stage of the negotiation.
The building’s own requirements should guide how much documentation you request.
For example, some buildings may have specific liquidity or financing requirements, while others may have different standards. A buyer who looks excellent on paper for one co-op may not fit another building’s rules.
This is also where communication matters. If the buyer, lender, attorneys, and managing agent are all working from consistent information, the transaction has a much better chance of moving smoothly.
Do not accept an offer simply because the number is attractive. Look at the entire package.
What Sellers Need to Know About Today’s Upper East Side Market
Selling a pre-war co-op in 2026 requires more precision than simply comparing your apartment with the highest recent sale.
Your building may have a different financing policy. Your line may be more desirable. Your maintenance may be higher or lower. Your apartment may be renovated while the closest comparable is not. There may be an assessment or capital project that changes the buyer’s calculation.
All of those details affect value.
For sellers, preparation should begin before the listing date. Review recent closed sales, identify your real competition, understand the building’s financial position, confirm flip-tax responsibility, and determine whether the apartment needs cosmetic work before photography.
Positioning matters just as much as preparation. A $1.25 million apartment competing against three similar listings at $1.15 million has a problem before the first showing. But an apartment priced appropriately for its building, condition, and buyer pool can create urgency.
The seller’s job is to make the value obvious.
That means presenting the apartment clearly, answering predictable questions before they become objections, and pricing against what buyers can choose today rather than what a similar apartment sold for at the market’s peak.
Timing Your Listing
There is no single perfect month to sell an Upper East Side co-op.
Seasonality matters, but the condition of your apartment and the competitive set matter more. Spring can bring more buyer activity, while fall can attract buyers who are ready to make decisions before the end of the year. Summer and holiday periods can be quieter, but a well-positioned apartment can still sell.
The bigger mistake is waiting for the “perfect” market while ignoring the apartment’s specific competition.
If three comparable apartments are already on the market, launching at the wrong price can make your listing easy to overlook. If there is very little comparable inventory, you may have more room to position strategically.
Timing should therefore be based on three things: your financial goals, your building’s current competition, and the buyer pool for your specific apartment.
What This Means for the Buyers You’re Trying to Reach
Your eventual buyer is probably comparing more than your apartment.
They may be comparing another co-op in the same building, a condo nearby, a different pre-war building, or an apartment that requires less renovation. They are also comparing the total cost of ownership.
That is why the strongest listing answers questions before buyers have to ask them.
How much is maintenance? Is there an assessment? What financing is permitted? Who pays the flip tax? Has the apartment been renovated? Are there any building projects underway? How does the apartment compare with recent closed sales?
The more clearly those questions are answered, the easier it becomes for a serious buyer to make a decision.
Selling a pre-war co-op is ultimately about reducing uncertainty. Buyers can handle differences in price, layout, condition, and building rules when they understand what they are getting in return.
The seller who explains those trade-offs clearly is usually in a much stronger position than the seller who simply lists at the highest number they can justify.
Ready to Sell Your Upper East Side Co-op?
If you’re thinking about selling a pre-war co-op on the Upper East Side, start with the building, the recent closed sales, your competition, and the costs that will affect your net proceeds.
From there, the same process applies to condos, newer development, and other Manhattan property types: understand the market, position the property correctly, and make the buyer’s decision easier.
If you want to talk through your specific apartment, building, pricing strategy, or broader NYC real estate plans, [email protected]
Frequently Asked Questions
The best way to price a pre-war co-op is to start with recent closed sales in the same building and then adjust for the apartment’s condition, floor, line, layout, maintenance, and financing structure.
A nearby sale can provide context, but it should not automatically become your primary comparable. A renovated apartment in a building with strong financials and favorable financing terms may command a different price from a similar-sized apartment in a building with higher carrying costs or stricter financing rules.
Current Upper East Side co-op pricing also varies substantially by submarket and apartment type, so neighborhood-wide medians are only a starting point
A flip tax is a fee charged by a co-op when an apartment is sold, and the amount and responsible party depend on the building’s governing documents.
Some buildings calculate the fee as a percentage of the sale price, while others may use a different formula. Current listing information for buildings such as 1120 Park Avenue and 1185 Park Avenue has shown a 2 percent purchaser-paid flip tax, but those terms should be confirmed for the specific apartment before you rely on them.
If the seller is responsible for the fee, it directly reduces net proceeds. If the buyer pays, the cost can still affect negotiations because buyers may factor it into their total acquisition budget.
Yes, you should understand a buyer’s financing plan and financial strength before accepting an offer, especially for a co-op with specific board or building requirements.
The exact information you need depends on the building, but proof of funds, mortgage preapproval, proposed down payment, and other relevant financial documentation can help you evaluate whether the buyer is positioned to complete the purchase.
The goal is not to collect every document before a buyer has even made an offer. It is to avoid accepting a high number from a buyer whose financing or financial profile may not work for the building.
A slightly lower offer from a well-qualified buyer can sometimes be more attractive than a higher offer with significant uncertainty.
A co-op sale can take several months from listing to closing, and the timeline depends on pricing, buyer demand, negotiations, financing, attorney review, and the building’s board process.
The listing period is only part of the timeline. After a contract is negotiated and signed, the buyer may still need to complete financing, prepare the board package, receive board approval, and schedule the closing.
That means sellers should plan around the entire transaction rather than assuming that finding a buyer means the sale is finished.
A properly priced apartment with complete documentation and a financially qualified buyer can eliminate some avoidable delays, but every building and transaction moves differently.
It can be a good time to sell if your apartment is priced and positioned against the competition that buyers can choose today.
The Upper East Side has a deep supply of co-op inventory, which means buyers have options. That makes accurate pricing particularly important. Recent Manhattan co-op data has shown a market where buyers remain active but continue to pay close attention to value, carrying costs, and building-specific factors.
For a seller, the question is less “Is the market good?” and more “How does my apartment compare with everything currently competing for the same buyer?”
That is the question your pricing strategy should answer.
Yes, but the difference is more about presentation than creating an entirely different style.
With a pre-war co-op, buyers often want to understand the apartment’s proportions, layout, architectural details, and condition. Furniture should help demonstrate scale and circulation rather than overwhelm the rooms.
Start by removing clutter, improving lighting, making repairs, and creating clear paths through the apartment. Highlight original details and strong architectural features rather than hiding them.
The objective is to make the apartment easy to understand online and in person. A buyer should be able to see how the rooms work, what makes the apartment distinctive, and what improvements may already have been completed.