Selling a condo on the Upper East Side means competing inside a market where ownership type changes the buyer’s math. One Q4 2025 Upper East Side dataset recorded 197 condo sales at a $2.4 million median and 344 co-op sales at a $1.0875 million median. Those are product medians, not values for a particular apartment, but they show why a blended neighborhood number is a weak pricing anchor.
The current market is not one clean statistic either. A Q2 2026 Upper East Side report covering all apartment types recorded 602 sales, a $1.25 million median, and average price per square foot of $1,376. A narrower East Side resale-condo table reported average price per square foot of $1,578, up 6% year over year. Different boundaries and product filters produce different answers. Your building, line, monthly cost, condition, and live competition still set the number.
Co-ops remained a majority of active Upper East Side inventory in a September 2026 listing snapshot, at 52%, while condos represented 36%. That is a meaningful difference, not an excuse to say the neighborhood is ‘overwhelmingly co-op’ or that condo buyers never compare the two. Some buyers begin condo-only. Others compare both and decide based on financing, approval, subletting, monthly cost, space, and intended hold period.
Start With the Buyer’s Real Decision
A typical resale condo does not use the co-op-style discretionary board approval and interview process. The buyer may still submit an application and need a waiver of the condominium’s right of first refusal if the governing documents require one. That distinction matters. Market the easier ownership process accurately, without promising that the building has no review step.
Financing can widen the buyer pool, but do not describe every co-op as 50% financing or all cash. Co-op limits are building-specific. Many require 20% to 30% down, some allow only 50% financing, and a small number require all cash. A condo buyer may have more financing flexibility, but the lender still underwrites both the borrower and the project.
Rental and resale flexibility is another advantage, but condos are not restriction-free. Declarations, bylaws, house rules, rent laws, lender rules, and short-term-rental restrictions still apply. The strongest marketing explains the actual rules of this condominium: lease term, application, fees, investor limits, move procedures, and any waiver process.
For a clean explanation of how the ownership structures affect value and flexibility, use this Upper East Side co-op versus condo comparison.
Price Against the Condo Market, Not One Headline Median
Start with closed condo sales in the same building and, when possible, the same line. Give the most weight to the last 12 months, then explain any time adjustment. Floor, exposure, usable layout, outdoor space, renovation quality, view, monthly cost, and assessment status matter more than neighborhood labels.
Next, study the condos a buyer can tour now. A competing listing is not automatically a comparable sale, but it sets the choice on the screen. If your building has three similar apartments available, buyers will rank price, condition, carrying cost, light, and seller motivation. A high asking price does not become evidence merely because a neighbor chose it first.
Use price per square foot carefully. The Q2 2026 East Side resale-condo average of $1,578 per square foot is a useful product-level benchmark, not a valuation formula. It can conceal differences between Yorkville, Lenox Hill, Carnegie Hill, Park Avenue, Fifth Avenue, prewar conversions, postwar towers, and boutique new development. Start narrow and widen only when the building evidence is thin.
If you want a current, building-level pricing read before choosing the asking price, contact Brett before the listing goes live.
Common Charges, Taxes, and Assessments Are Part of the Price
Condo buyers compare the full monthly obligation: mortgage, common charges, property taxes, insurance, and assessments. A unit with higher carrying costs can still command a premium for space, services, reserves, or condition, but the seller should explain the trade rather than leave the buyer to discover it.
The condo and co-op numbers are structured differently. A condo owner generally receives a separate property-tax bill and pays common charges for building operations. A co-op corporation receives the building-wide tax bill, and the shareholder’s maintenance can include the allocated property tax, operating expenses, and debt service on an underlying mortgage where one exists. Do not compare common charges with maintenance without adding the condo’s separate tax bill.
Prepare the evidence: current common charges and taxes, assessment amount and duration, recent increases, budget, financial statements, insurance, capital projects, litigation, and reserve information. An assessment is not automatically fatal. A surprise assessment discovered late is what creates leverage for the buyer.
Know the Competition From New Development
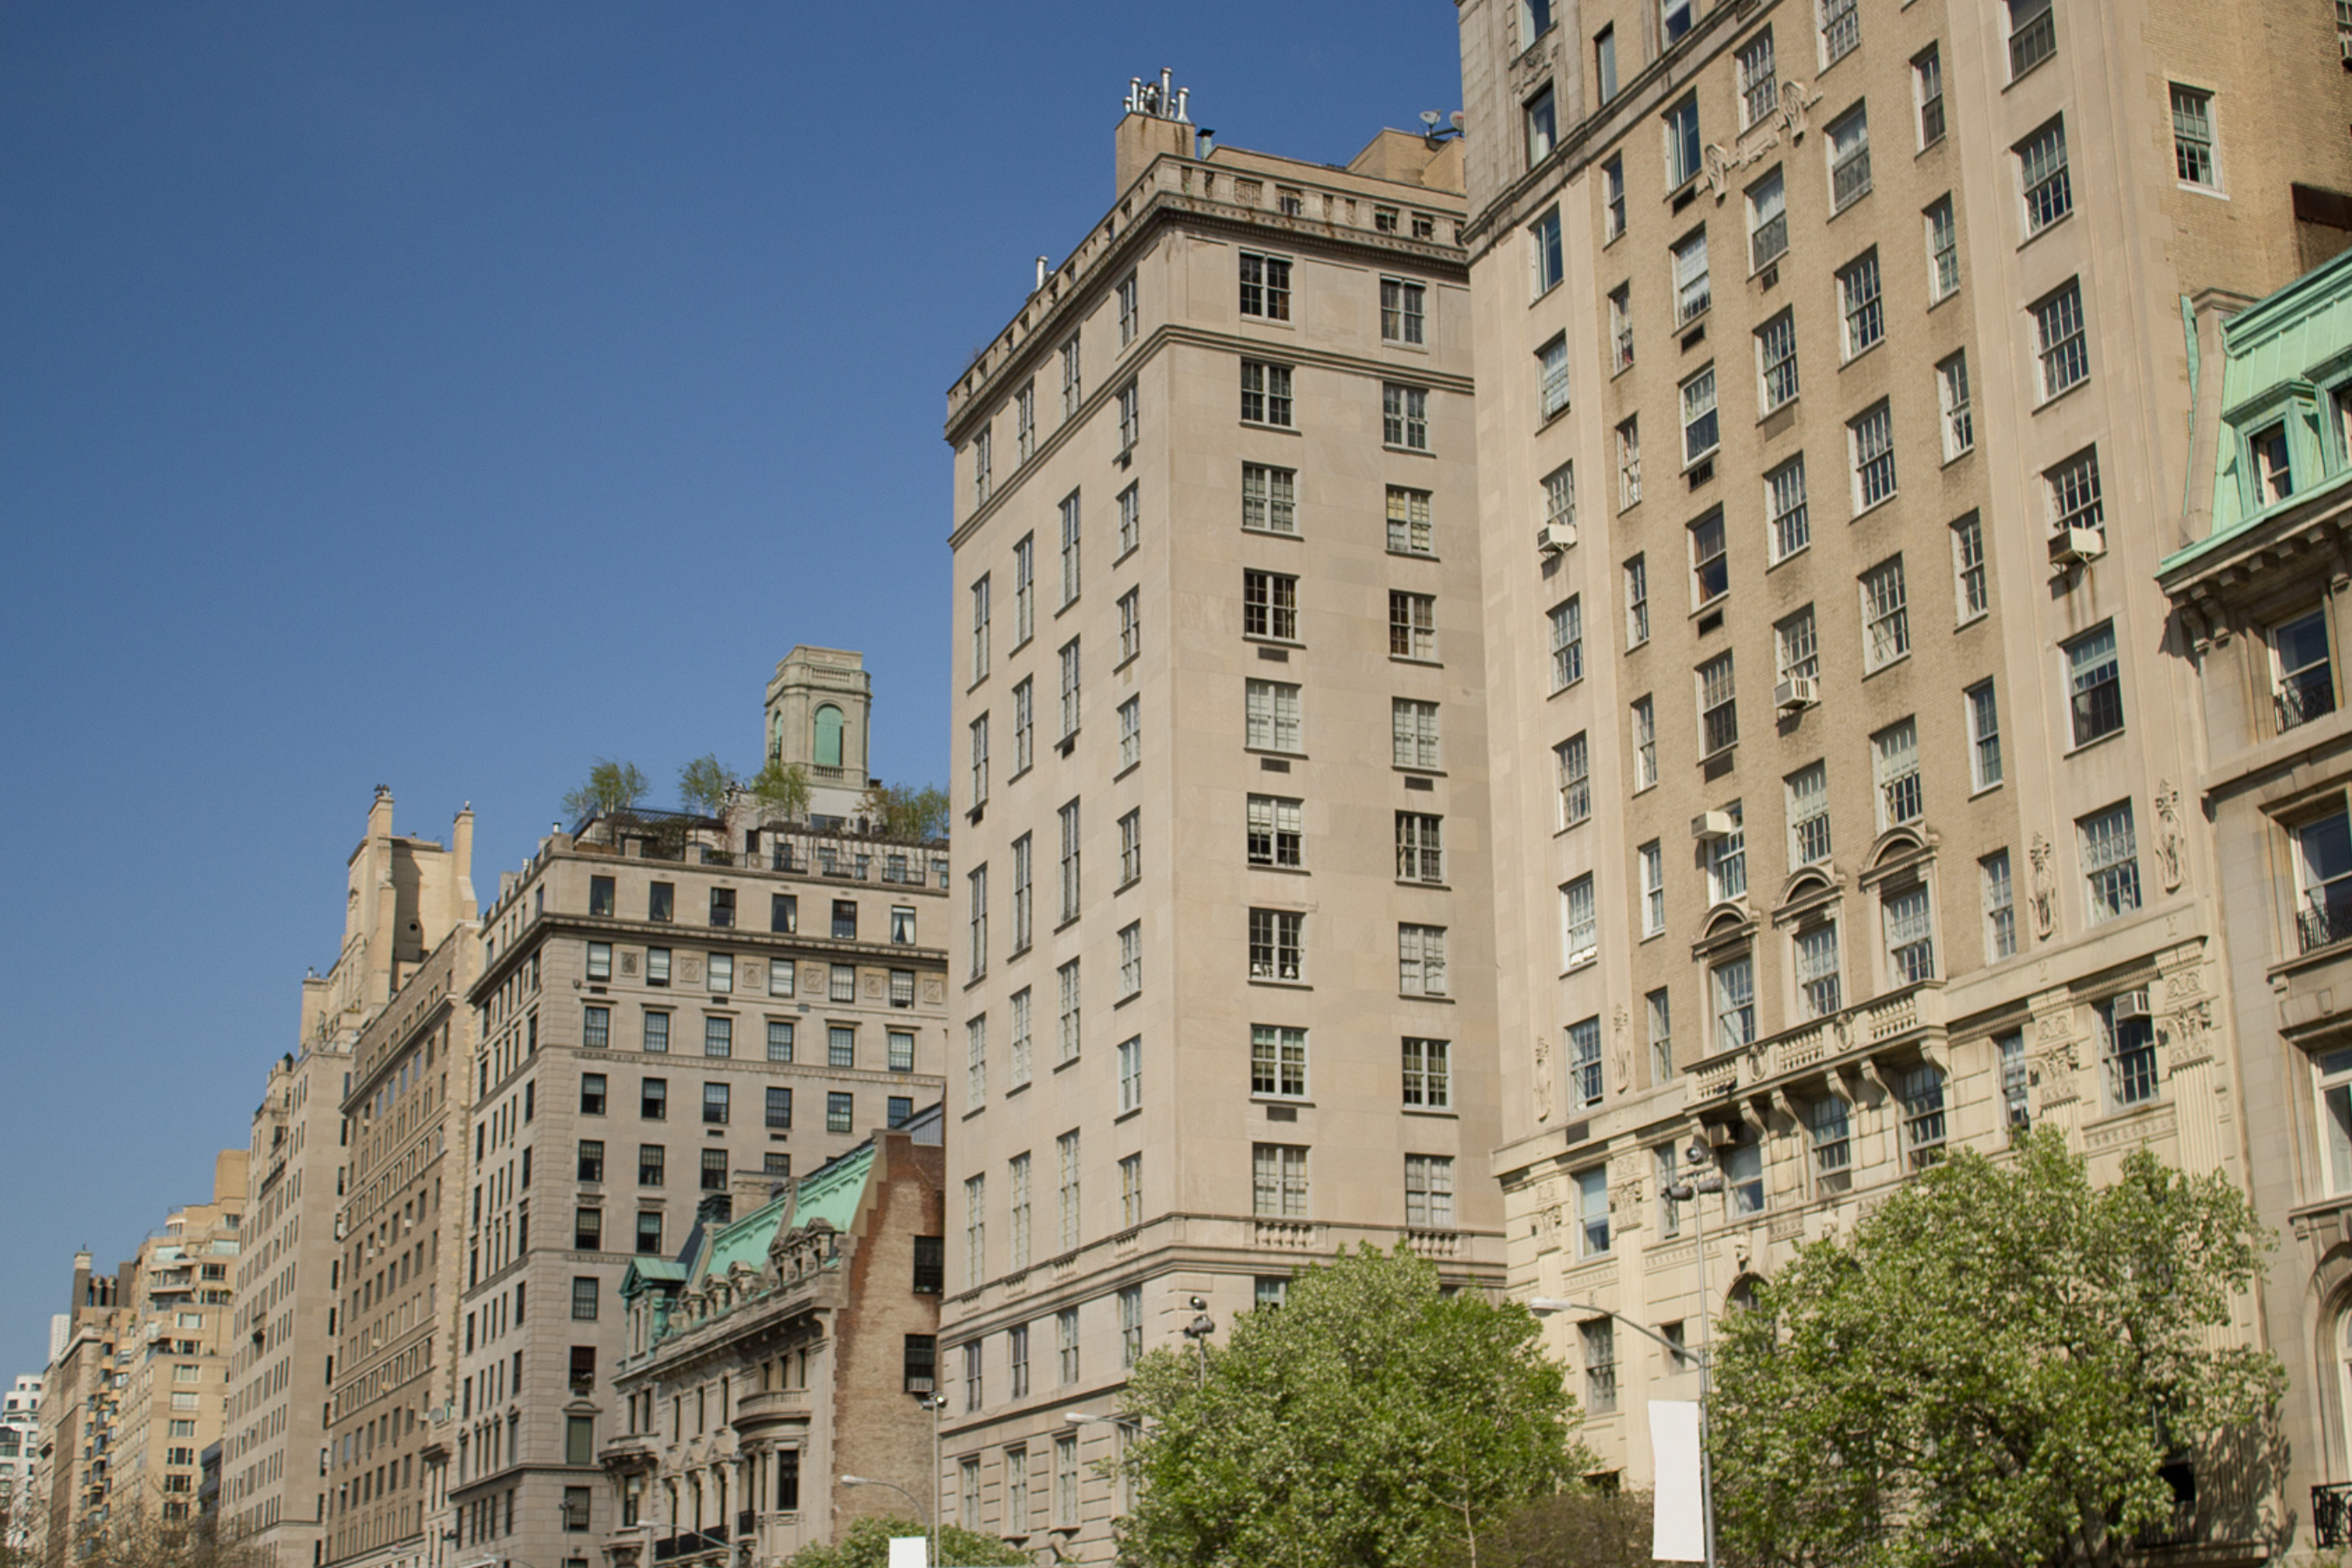
Resale sellers also compete with sponsor inventory, especially at the upper end. Two current examples make the point. The official site for 200 East 75th Street describes a 35-residence building with immediate occupancy. Public 2026 records describe 255 East 77th Street as a 62-residence condominium that opened in 2026. A resale seller does not need to imitate those buildings, but should understand the finishes, amenities, concessions, and presentation the buyer sees.
Your resale can offer advantages: the apartment already exists, the view and condition can be inspected, the building has an operating history, and a conventional resale contract usually does not shift the sponsor’s transfer taxes and legal fee to the buyer. At a price above $500,000 but below $3 million, shifted NYC and New York State seller transfer taxes alone total approximately 1.825%, before sponsor counsel or building contributions.
Compare net economics, not brochure prices. A sponsor unit with a closing credit may cost less than its published price suggests. A resale with lower purchase costs but an assessment may not. Your broker should calculate both scenarios from the actual terms rather than declare resale automatically cheaper.
What the Buyer Pays at Closing
Buyer closing costs depend on financing, purchase price, and whether the unit is resale or sponsor inventory. A financed resale condo often uses roughly 2% to 4% as a preliminary planning range. A sponsor condo may run roughly 4% to 6% or more because the contract can add shifted transfer taxes, sponsor counsel, working capital, title, mortgage recording tax, and building charges. These are estimates, not statutory totals.
New York State’s mansion tax is 1% on qualifying residential consideration of $1 million or more. A separate New York State supplemental tax applies to qualifying New York City residential conveyances at $2 million or more. Combined, the buyer-side rates are 1% from $1 million to under $2 million; 1.25% from $2 million to under $3 million; 1.5% from $3 million to under $5 million; 2.25% from $5 million to under $10 million; 3.25% from $10 million to under $15 million; 3.5% from $15 million to under $20 million; 3.75% from $20 million to under $25 million; and 3.9% at $25 million or more.
The bracket example must be exact. At $1.999 million, the buyer pays $19,990. At $2.02 million, the combined tax is $25,250. The tax difference is $5,260, while the price difference is $21,000. The buyer’s total reduction from $2.02 million to $1.999 million is $26,260 before financing effects. It is not a $25,000 tax saving.
Where the Negotiation Can Move
Price is only one term. A straightforward condo can target roughly 30 to 60 days after a fully executed contract, but financed transactions, title, application, waiver, and scheduling issues can push the closing to 60 to 90 days or more. Treat timing as a planning range, not a promise. Ask what date the buyer actually needs.
Financing certainty matters too. Review the preapproval, down payment, proof of funds, financing contingency, lender familiarity with the building, and whether the buyer has enough cash for closing costs and post-closing reserves. A cash offer is not automatically better, and a financed offer is not automatically risky. Compare complete terms and execution evidence.
Near a tax threshold, show both parties the real arithmetic. A price change can alter the buyer’s tax and loan, but the seller gives up the price reduction dollar for dollar. The useful negotiation is the full buyer cash and seller net, not a dramatic but incorrect statement about the mansion tax.
Prepare the Apartment and the Building File Together
Presentation matters because buyers compare resale condition with renovated and sponsor inventory. Start with repairs that are visible and understandable: fresh paint where needed, corrected lighting, functioning doors and fixtures, clean windows, repaired damage, and floors that show well. A full renovation does not reliably return its cost and should never be promised as positive ROI without building-specific comps.
The paperwork deserves equal attention. Gather financial statements, current budget, common-charge and tax history, assessment information, insurance, alteration agreements, open permits, litigation disclosures, house rules, application requirements, and the right-of-first-refusal procedure before launch. The statutory Property Condition Disclosure Statement generally does not cover condo or co-op units, but contract, anti-fraud, lead-paint, offering-plan, and governing-document obligations still matter.
Early preparation lets the seller price known issues instead of negotiating under pressure later. It also helps the buyer’s lawyer and lender finish diligence without waiting for basic records. Speed comes from complete information, not from pretending the building has nothing to review.
Use the Launch as a Test, Not a Myth
New listings receive attention because active buyers have already seen the older inventory. Review showing volume, saved-listing activity, questions, feedback, offers, and competing price changes during the first 10 to 14 days. That is a useful checkpoint, not proof that every apartment has a fixed two-week expiration date.
Do not wait a mandatory six weeks to react. If buyers consistently reject the same feature or the apartment receives little qualified traffic, compare the evidence with active and newly closed alternatives. The answer may be price, presentation, access, photography, monthly costs, or a missing explanation in the listing.
Inventory in the building matters more than seasonality slogans. Launching beside two nearly identical units creates a direct comparison, but waiting is not automatically better if new supply is coming. Current Upper East Side development reporting expected additional sponsor inventory in fall 2026, so the decision should consider what is likely to enter the market as well as what is live today.
If You’re Selling an Upper East Side Condo
Build a seller net sheet before choosing the asking price. Include negotiated brokerage compensation, NYC and New York State transfer taxes, attorney fees, mortgage payoff and satisfaction charges, managing-agent and move-out fees, prorations, concessions, unpaid common charges, and any building-specific transfer contribution. For an ordinary individual residential sale above $500,000 and below $3 million, NYC and New York State transfer taxes generally total 1.825%; at $3 million or more, the ordinary combined rate generally becomes 2.075%.
Price from closed condo evidence, then position against the active resale and sponsor units a buyer can choose. Explain the monthly cost, ownership flexibility, building history, recent work, assessment status, and closing economics accurately. Do not claim that every condo buyer has rejected co-ops, that every co-op requires 50% down, or that the lower monthly number always wins.
Qualify the offer, prepare the building file, and decide your priorities before bids arrive. Know the target price, minimum acceptable net, preferred closing window, financing tolerance, and position on contingencies. That preparation makes the negotiation cleaner because the seller can compare probability and timing alongside the headline price.
Selling a Condo on the Upper East Side: Set the Number From the Building Out
The best pricing evidence is local: the same building, same line, similar floor, similar condition, and recent closing date. Market reports explain direction and product differences, but they cannot price a specific apartment. Common charges, taxes, assessments, and current alternatives complete the comparison.
The condo buyer pool is different, but not monolithic. Some buyers value financing flexibility, deeded ownership, and easier leasing. Others will still compare the space and monthly cost of a co-op. Market the actual advantages of this condominium, prepare the facts behind them, and price where the evidence gives buyers a reason to act.
If you’re weighing an Upper East Side condo sale or another New York City real-estate move, contact Brett for a building-level pricing and launch strategy.
Frequently Asked Questions
There is no single reliable Upper East Side condo median that prices every apartment. Different 2026 sources use different boundaries and product filters. One Q2 report covering all Upper East Side apartments recorded a $1.25 million median and $1,376 average price per square foot, while a narrower East Side resale-condo table reported $1,578 average price per square foot. A Q4 2025 UES dataset reported a $2.4 million condo median, but its mix included higher-priced product. For a specific unit, start with closed condo sales in the same building and line, generally within 12 months, then adjust for floor, exposure, condition, layout, monthly costs, outdoor space, and assessments.
Use co-ops as buyer-context, not as primary valuation comparables. A condo and co-op on the same block can differ in ownership, approval, financing, leasing, taxes, monthly costs, and closing expenses. Some buyers search condo-only, but others compare both structures and trade flexibility for space or lower price. Price from condo sales in the same building or a genuinely competitive condo set. Then use nearby co-ops to anticipate buyer objections about monthly cost, usable space, and value. The goal is not to ignore the larger co-op market. It is to avoid blending unlike products into one median and calling the result a condo valuation.
A typical resale condo does not use a co-op board’s broad discretionary purchaser-approval and interview process. The buyer may still need to submit a purchase application, provide financial and identification documents, pay building fees, and obtain a waiver of the condominium’s right of first refusal if the declaration or bylaws require one. Sponsor sales can use a different procedure. The governing documents control, so listing copy should not promise “no board process” without checking the building. Sellers should obtain the current application, fee schedule, insurance requirements, waiver timing, and move rules before launch so the buyer receives accurate information.
A straightforward condo can target roughly 30 to 60 days from a fully executed contract to closing, but 60 to 90 days or more is possible. Financing, appraisal, title, lender project review, managing-agent documents, the condo application, right-of-first-refusal waiver, insurance, scheduling, and another linked transaction can extend the timeline. The marketing period comes before that and depends on price, condition, access, and competing inventory. Sellers can reduce avoidable delays by preparing financial statements, assessment information, insurance, alteration records, and building procedures before accepting an offer. The contract’s closing language controls; a planning range is not a guaranteed closing date.
The total depends on price, financing, and whether the apartment is a resale or sponsor sale. A financed resale condo may use roughly 2% to 4% as an initial planning range, while a sponsor condo may run 4% to 6% or more if the contract shifts transfer taxes, sponsor counsel, working capital, and other charges to the buyer. A financed condo can include mortgage recording tax, title insurance, lender fees, attorney fees, recording, building charges, and prepaids. New York’s 1% mansion tax starts at $1 million, and a separate supplemental tax applies to qualifying NYC residential purchases at $2 million or more. Obtain a transaction-specific estimate.
Renovate only when the expected improvement in marketability or net proceeds justifies the cost, approval time, permitting, and execution risk. Fresh paint, better lighting, repairs, clean windows, improved floors, decluttering, staging, and strong photography often solve more visible problems than a full renovation. Compare the apartment with current resales and sponsor inventory in the same price band. If buyers will discount the unit for an obsolete kitchen or bath, price that trade honestly or obtain contractor estimates before deciding. Never assume a renovation automatically returns its cost. The building’s alteration agreement, insurance requirements, work hours, deposits, and approval timeline also belong in the calculation.