Selling an apartment in Kips Bay near $1 million creates a pricing decision that looks simpler than it is. At $999,000, a qualifying residential buyer owes no mansion tax. At exactly $1 million, the buyer owes $10,000. That cliff can influence searches and negotiation, but it does not turn $999,000 into the right price for every apartment.
The seller still needs building-level evidence: recent closed sales, current competition, ownership type, monthly charges, assessments, condition, and likely buyer costs. A neighborhood median cannot price a specific line, and a new-development ask is not automatically a resale comparable. Start with the seller’s probable net and probability of closing, then work backward to the launch strategy.
Why a Neighborhood Median Is Only Context
Kips Bay includes condominiums, cooperatives, sponsor inventory, older resales, studios, large family apartments, and penthouses. Blending them into one neighborhood number can hide more than it reveals. A condo and a co-op at the same price may carry different buyer costs, financing rules, application procedures, and monthly expenses.
Start with closed sales in the same building and line, ideally within the most recent six to 12 months when enough evidence exists. Adjust for floor, exposure, usable layout, legal bedroom count, condition, outdoor space, renovation quality, monthly charges, assessments, storage, and seller type. Then compare active listings buyers can choose today and any sponsor concessions that change effective price.
Neighborhood boundaries are also informal in this part of Manhattan. Some marketing sources use Kips Bay, Gramercy, Rose Hill, or NoMad for nearby addresses. The objective inputs are the address, building, ownership form, apartment characteristics, and closest alternatives, not the label that produces the most flattering median.
Read the threshold alongside the current Kips Bay real estate market trends in 2026, not as a substitute for building-level evidence.
Current Kips Bay Building Examples
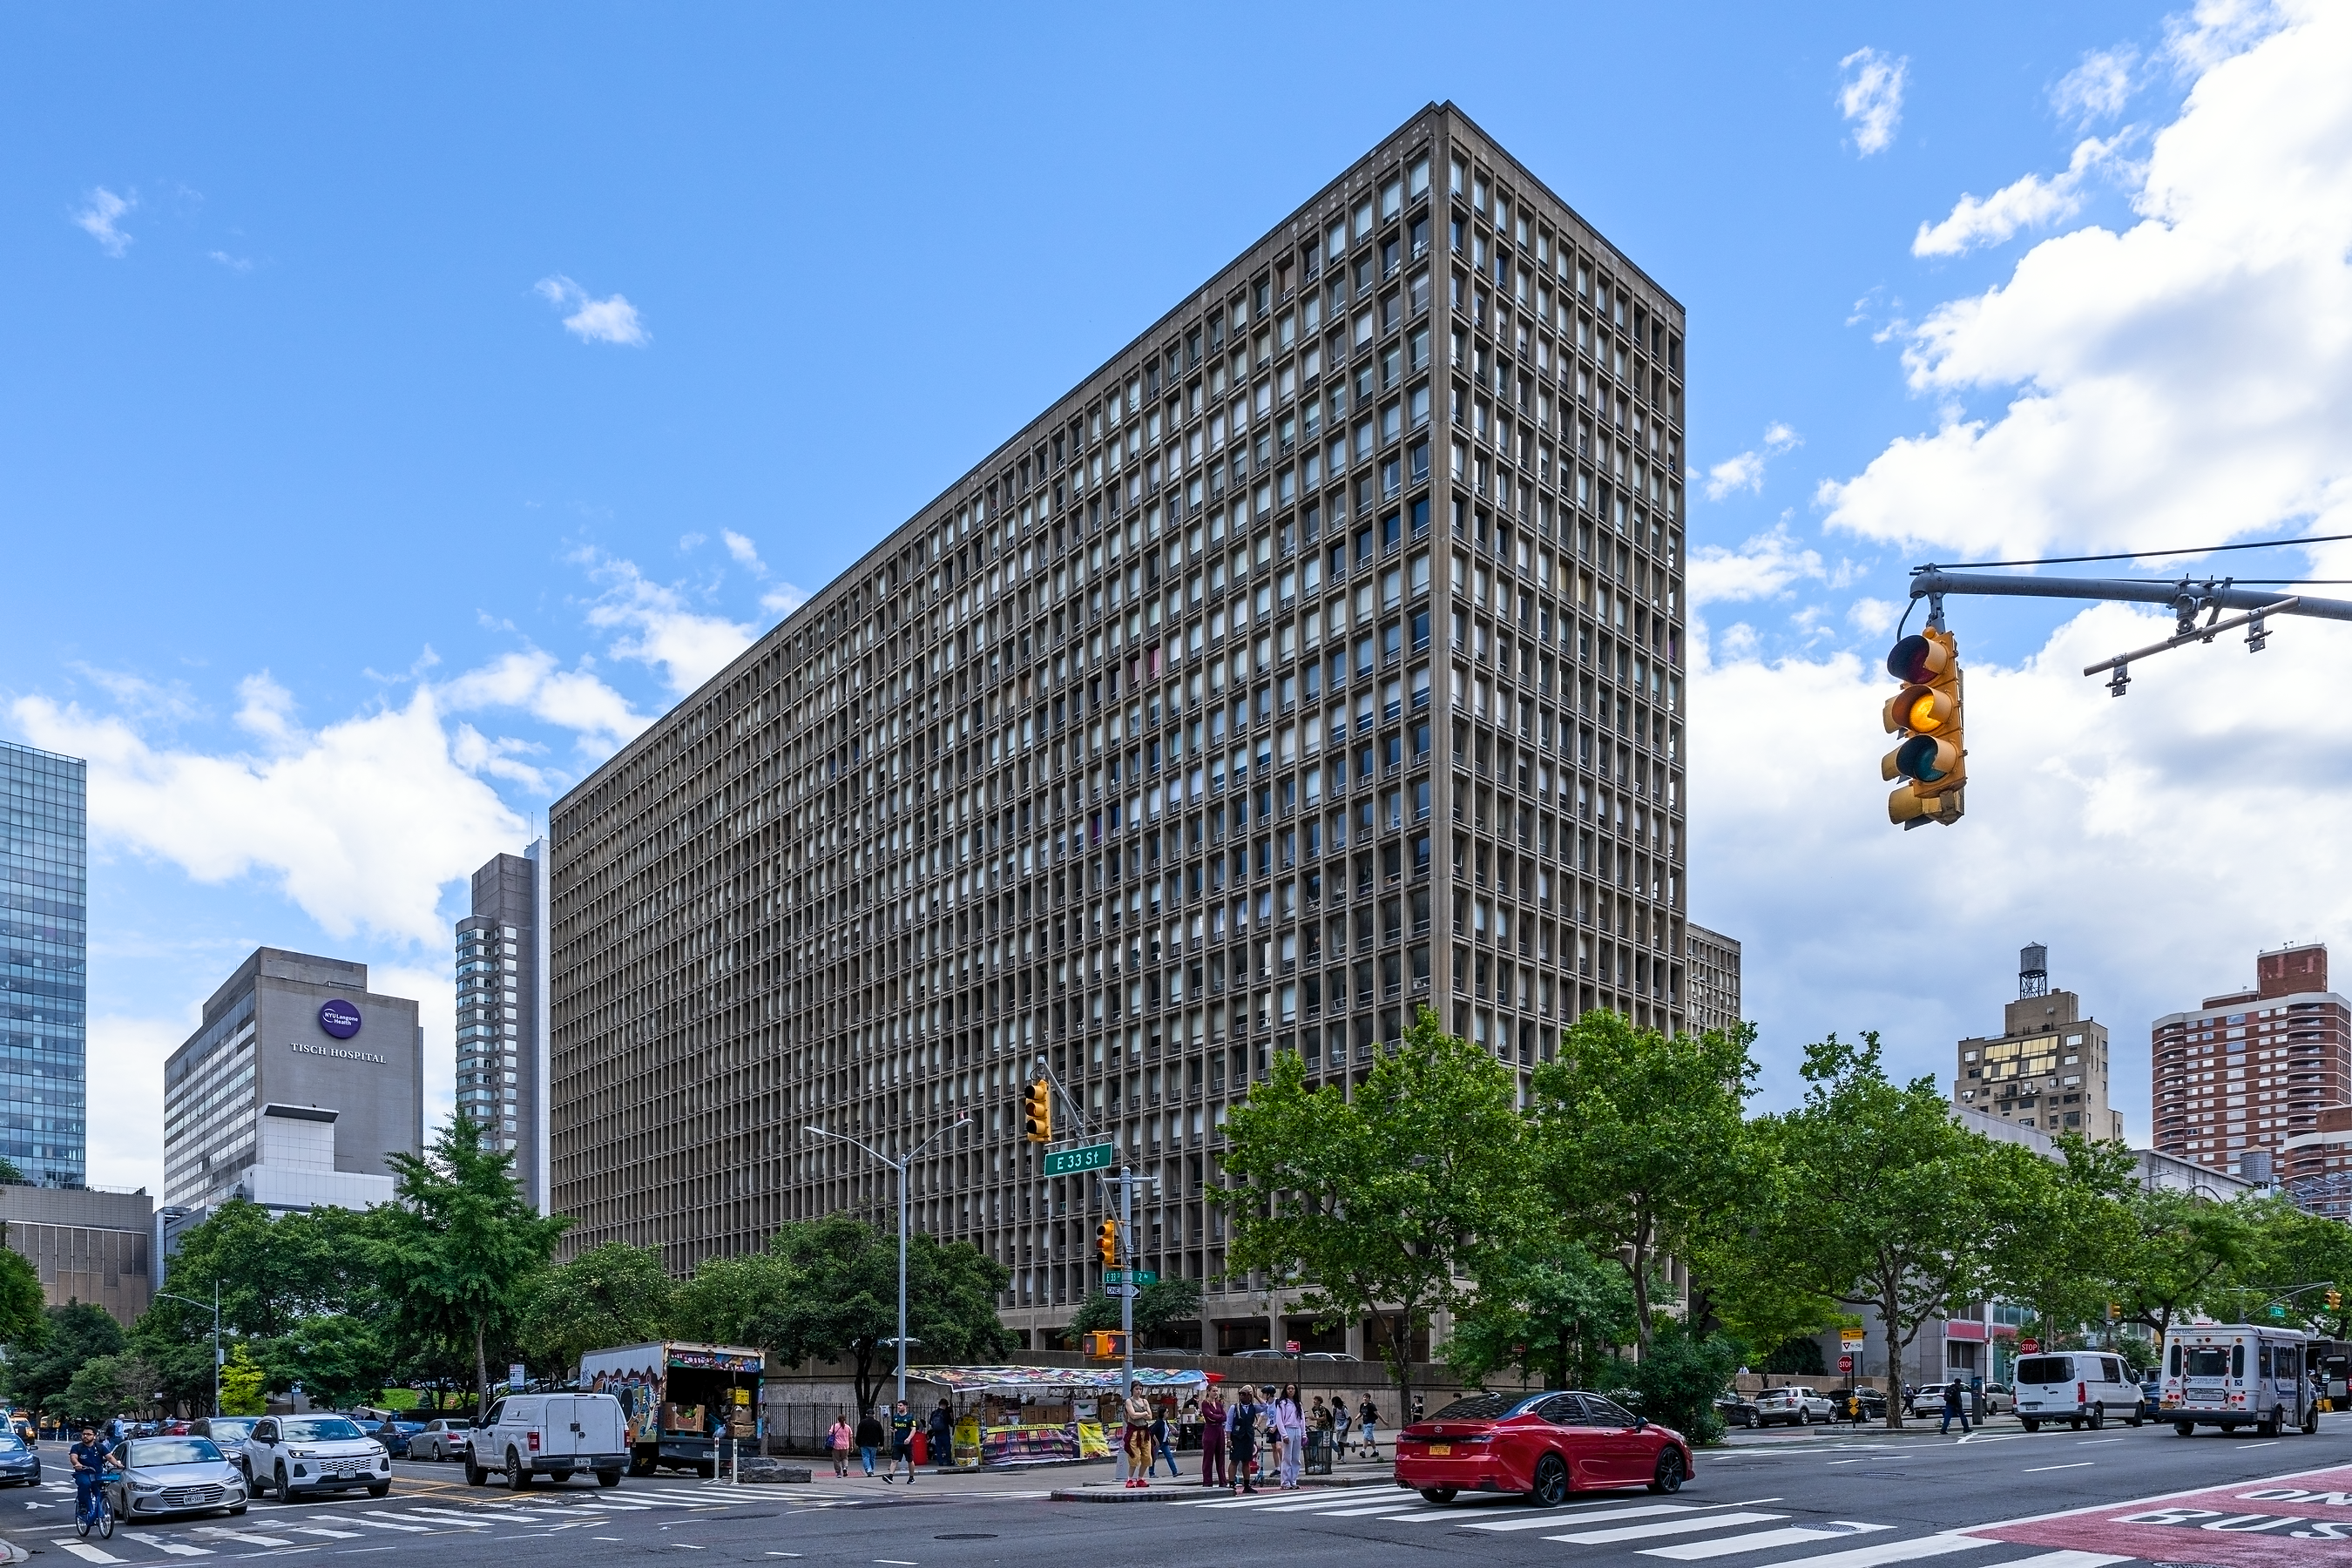
Eastlight at 501 Third Avenue
Eastlight is a 144-residence condominium under Attorney General plan CD200130. StreetEasy’s listing history for Residence 20E shows a $1.695 million ask and a $1.5 million closing-record sale dated February 12, 2026. Residence 32B, a one-bedroom sponsor unit, was listed at $1.615 million on June 30, 2026. These figures show why sponsor status, floor, exposure, and concessions must be checked before using a price as a resale comparison.
Hendrix House at 250 East 25th Street
Hendrix House is a condominium, not a co-op. Its Attorney General record, filed under the legal name 429 Second Avenue Condominium, lists 59 residential units. Launch and brokerage materials marketed 60 residences, so 59 should be used as the legal plan count while 60 is identified only as marketing language. A two-bedroom sponsor residence was reduced to a $1.805 million ask in January 2026; the original draft incorrectly called that apartment a one-bedroom.
VU at 368 Third Avenue
VU is a 100-residence condominium under plan CD190151. Residence 32A, a three-bedroom, sold for $3.795 million on March 31, 2026 according to the cited closing record. PH34A was asking $8.695 million after an April 17, 2026 reduction. Those high-end examples are useful only when the subject apartment competes with similar size, views, finish, and building position.
Kips Bay Towers and Hillrose28
Kips Bay Towers is a condominium complex, not a co-op. Its official site and CityRealty use 1,118 units, while StreetEasy lists 1,120 across the complex. The public sources do not explain the difference, so identify the source rather than guessing. Residence 12K at 333 East 30th Street was listed at $899,000 on April 8, 2026 and sold for $890,000 on June 15, 2026.
Hillrose28 is a 43-residence condominium under plan CD190173. Residence 1402 was initially listed at $3.25 million, reduced to a $2.995 million last ask, and sold for $2.85 million on February 9, 2026. Neither Kips Bay Towers nor Hillrose28 should be presented as a co-op-board or co-op flip-tax example.
The $1 Million Buyer-Tax Threshold
The New York State mansion tax is 1% of the relevant residential consideration at $1 million or more. A separate New York State supplemental tax applies to qualifying NYC residential conveyances beginning at $2 million. Combined buyer-side mansion and supplemental rates are 1% from $1 million to below $2 million, 1.25% from $2 million to below $3 million, 1.5% from $3 million to below $5 million, 2.25% from $5 million to below $10 million, 3.25% from $10 million to below $15 million, 3.5% from $15 million to below $20 million, 3.75% from $20 million to below $25 million, and 3.9% at $25 million or more.
At $999,000, the buyer pays no mansion tax. At $1 million, the buyer pays $10,000, so price plus mansion tax rises by $11,000 for a $1,000 price increase. At $1.01 million, the mansion tax is $10,100 and the buyer’s price-plus-tax outlay is $21,100 more than at $999,000. The applicable rate is a cliff rate on the relevant consideration, not a marginal rate on dollars above the threshold.
For the seller, ordinary transfer taxes increase by only $18.25 between $999,000 and $1 million under the standard 1.825% resale stack. The threshold changes buyer cash, not the seller’s statutory rate. Price below it only when comparable sales, search behavior, and likely net support that choice.
For a building-level pricing and net analysis before launch, contact Brett to test the threshold against current competition.
Seller Transfer Taxes and the Net Sheet
For an individual residential condominium unit or cooperative apartment priced above $500,000 and below $3 million, the ordinary seller-side transfer-tax stack is 1.425% NYC Real Property Transfer Tax plus 0.4% New York State base transfer tax, or 1.825%. At $3 million or more, the 0.25% New York State additional base tax applies, bringing that stack to 2.075%. At exactly $3 million, those seller transfer taxes total $62,250 under the stated assumptions.
Brokerage compensation is negotiable and has no mandatory legal percentage. Add the seller’s attorney, managing-agent charges, move-out costs, payoff and satisfaction charges, prorations, concessions, and any private building transfer fee. Mortgage payoff reduces cash proceeds but should be shown separately from transaction costs. Capital-gains tax is a separate tax-planning question requiring the seller’s own tax adviser.
Build a net sheet at the asking price, a realistic contract price, and the lowest acceptable outcome. Recalculate it after every counteroffer. At $1.015 million, reducing the price to $999,000 cuts gross price by $16,000 and saves the buyer $10,150 of mansion tax. Buyer outlay falls by $26,150, while seller statutory transfer taxes fall by about $292. Before other costs, seller proceeds fall by about $15,708.
Selling a Condo in Kips Bay
A condo resale often involves less purchaser screening than a co-op, but it is not board-free. The declaration and bylaws may require a transfer package, fees, and a waiver of the right of first refusal. The governing documents control the response period; there is no universal statutory 30-day condo rule.
The contract should set a target closing date, but there is no universal 45-to-75-day legal timeline for a financed condo resale. Financing, appraisal, title, insurance, managing-agent documents, and any waiver procedure can extend the transaction. Market a condo as more predictable only when the building process and buyer support that claim.
A resale condo may have a buyer-cost advantage over sponsor inventory if the sponsor contract shifts seller transfer taxes, sponsor counsel, working capital, or other charges. Use the actual sponsor contract and concessions. Do not claim that every resale is cheaper merely because it is not a first sale.
Selling a Co-op in Kips Bay
Kips Bay includes co-ops, but Kips Bay Towers and Hillrose28 are not among them. For an actual co-op, confirm the application, financing limit, liquidity standard, interview process, proprietary lease, transfer requirements, and private transfer fee before listing. Financial criteria must be objective, lawful, and applied consistently.
A co-op flip tax is a private building transfer fee, not a government tax. It may use sale price, profit, shares, or a flat amount and must be authorized by the governing documents. The proprietary lease, bylaws, offering plan, properly adopted amendments, and contract determine the formula and payer. Never apply a generic percentage without written confirmation.
Review execution risk alongside price. A slightly lower offer with sufficient cash, realistic financing, and a complete board package may outperform a higher offer with greater approval risk. That does not make the lower offer automatically better, and financial screening cannot be used as a proxy for any protected characteristic.
Common Charges, Maintenance, and Assessments
Buyers compare total monthly cost, not only asking price. For a condo, disclose common charges, separate property taxes, insurance expectations, and assessments. For a co-op, show maintenance, assessments, underlying-mortgage context where relevant, and included services. Explain any temporary subsidy or known change.
If monthlies exceed nearby competition, the price or marketing should explain what the difference supports. Larger space, staffing, amenities, reserves, completed capital work, or tax treatment may justify it. Prepare the current budget, audited financial statements, insurance summary, assessment history, and capital-project information before launch so diligence does not create avoidable renegotiation.
Negotiating a Kips Bay Sale
Compare offers by estimated net and closing certainty rather than headline price alone. Review financing, appraisal risk, board or waiver process, concessions, sale contingencies, proposed timing, and the carrying cost of delay. A strong price with weak execution can produce a worse result than a slightly lower but credible offer.
Near $1 million, calculate both sides precisely. The buyer may be reacting to a real cash cliff, but the seller should compare that saving with the price surrendered and the probability of reaching another buyer. Timing can also carry value when the requested schedule is supported by financing and building procedures rather than a hopeful promise.
Preparing the Apartment and Paperwork
Presentation matters because buyers may compare an established apartment with staged sponsor inventory. Fresh paint, repairs, lighting, decluttering, an accurate floor plan, and strong photography can improve the launch without requiring a full renovation. If square footage or exclusive-use rights are advertised, retain reliable support for the claim.
Prepare the building records at the same time. Condo sellers should gather the resale package, budget, financials, insurance, assessments, waiver requirements, and fees. Co-op sellers should add the proprietary lease, board application, financing rules, liquidity guidance, interview process, and flip-tax formula. Also organize renovation approvals, warranties, appliance records, attorney details, and a current payoff estimate.
State known capital work and assessments accurately, including the remaining balance, schedule, purpose, and expected contract allocation. Pricing around a disclosed issue at launch is cleaner than discovering it after weeks of legal diligence.
Who the Apartment Competes With
A condo resale may compete with Eastlight, Hendrix House, VU, Hillrose28, Kips Bay Towers, or other buildings depending on price, size, monthly costs, and condition. New-development asks are not closed resale comparables, especially when sponsor concessions or shifted closing costs change effective price.
A co-op should be compared with genuine co-op inventory. Match ownership type, financing rules, board standards, monthlies, line, condition, and size. Accurate positioning attracts buyers already seeking the product instead of borrowing a median or neighborhood label that does not fit the apartment.
Build the Marketing Around Verifiable Value
Lead with facts a buyer can compare: legal bedroom count, documented interior size, floor, exposure, condition, outdoor space, storage, monthly charges, taxes, assessment terms, improvements, and building financials. Avoid vague claims that the apartment is a value because Kips Bay sits below another neighborhood in one snapshot.
For condos competing with sponsor inventory, show the resale closing-cost and timing comparison using current terms. For co-ops, disclose lawful financing and board requirements early enough that buyers can evaluate fit before contract. Track showing volume, repeat visits, questions, and offer quality during the first two weeks. If buyers repeatedly choose another unit, diagnose price, condition, monthly cost, layout, or building-level risk before making small, reactive reductions.
Selling an Apartment in Kips Bay: Set the Net First
Price from the building and line, model the $1 million buyer-tax threshold, calculate seller transfer taxes and private fees, and prepare the records before launch. The neighborhood is context; the seller’s net and probability of closing drive the decision. Set an asking strategy, expected contract range, and walk-away net before the first offer arrives, then update them as market evidence changes.
If you are selling in Kips Bay or planning another New York City real estate move, contact Brett to compare pricing, buyer costs, and likely proceeds.
Frequently Asked Questions
Price it against recent closed sales in the same building and line, then adjust for floor, exposure, legal layout, condition, outdoor space, monthly charges, assessments, and ownership type. Add active listings and sponsor inventory that buyers can choose now, but separate asking prices from closed evidence and account for concessions or shifted costs. A neighborhood median blends condos, co-ops, apartment sizes, and conditions, so it is context rather than an appraisal. If comparable evidence is thin, widen the search carefully by building quality, location, and apartment characteristics. The launch price should reflect the likely contract range, seller net, and current competition, not simply the highest nearby ask.
Only if comparable sales support a value near the threshold. At $999,000, a qualifying residential buyer pays no mansion tax. At $1 million, the buyer pays $10,000, so price plus mansion tax rises by $11,000 for a $1,000 price increase. Listing below the line may widen search filters and reduce buyer cash, but the seller still gives up price. If the building and line support $1.1 million, the threshold should not force an artificial discount. Model the buyer’s outlay, the seller’s transfer-tax savings, expected negotiation, and the likelihood of attracting another buyer before choosing the ask.
For an individual residential condo or co-op above $500,000 and below $3 million, the ordinary seller-side stack is generally 1.425% NYC RPTT plus 0.4% NYS base transfer tax, totaling 1.825%. At $3 million or more, the 0.25% NYS additional base tax generally raises that stack to 2.075%. The buyer ordinarily pays the mansion tax and NYS supplemental tax applicable to qualifying NYC residential transfers. Brokerage compensation, attorney fees, building charges, concessions, move-out costs, and mortgage-related charges also affect proceeds. Contract terms, exemptions, property classification, or a bulk transaction can change the result, so the attorney should confirm the exact closing statement.
You pay a flip tax only when the building documents and contract make you responsible for an authorized private transfer fee. A co-op formula may use sale price, profit, shares, or a flat amount. The proprietary lease, bylaws, offering plan, amendments, and stock-transfer documents should be checked. A condo may have transfer contributions or administrative fees under its declaration, bylaws, rules, and fee schedule, but it does not use a co-op proprietary lease. Kips Bay Towers and Hillrose28 are condominiums and should not be treated as generic co-op flip-tax examples. Obtain the current fee schedule and have the seller’s attorney verify the authority and payer before calculating net proceeds.
The timeline depends on ownership type, financing, title, appraisal, building documents, and buyer readiness. There is no universal legal 45-to-75-day condo timeline. A condo transfer package and right-of-first-refusal waiver can extend the process, while a co-op requires a board package and consent. For covered NYC co-op applications submitted on or after July 28, 2026, Local Law 58 requires acknowledgment within 15 days and a decision within 45 days after a complete application is acknowledged or deemed complete, subject to permitted extensions and summer-recess tolling. The law governs board response timing; it does not guarantee approval or a fixed closing date.
Prepare the current budget, audited financial statements, insurance summary, monthly-charge history, assessments, capital-project records, transfer package, and fee schedule. Condo sellers should confirm waiver requirements and transfer contributions. Co-op sellers should add the proprietary lease, board application, financing rules, liquidity guidance, interview process, and flip-tax formula. Also gather a mortgage payoff estimate, attorney details, renovation approvals, warranties, appliance records, and support for claimed square footage or exclusive-use rights. If an assessment exists, explain its remaining balance, schedule, purpose, and expected contract allocation. Complete records help the buyer’s attorney and lender assess the transaction without discovering material facts late.