Selling a FiDi condo with a view at risk starts with the evidence, not a prediction. A Financial District condominium with a memorable outlook can create an immediate emotional response and a harder question: what is being promised, and what can a seller responsibly know about the future? There is no basis to allege a specific view risk without property-specific evidence. The better approach is to treat the outlook as a valuable present condition, investigate the surrounding facts, and use language that is accurate when published.
Manhattan views are not necessarily perpetual property rights. In Schaefer v. Dehauski, a New York appellate court rejected a blocked-view claim where the owners had not shown an express easement; that case concerned a fence, not a FiDi tower, and does not decide the rights of any particular condo. A window may face a street, park, water, landmarked building, or development site with a different legal and planning history. A declaration, offering plan, easement, zoning district, permit, or public project can matter more than a sales photograph. Use records to answer questions, not manufacture fear. Make the view easy to understand, verify, and value without overstating certainty.
Selling a FiDi Condo With a View at Risk: Document Today
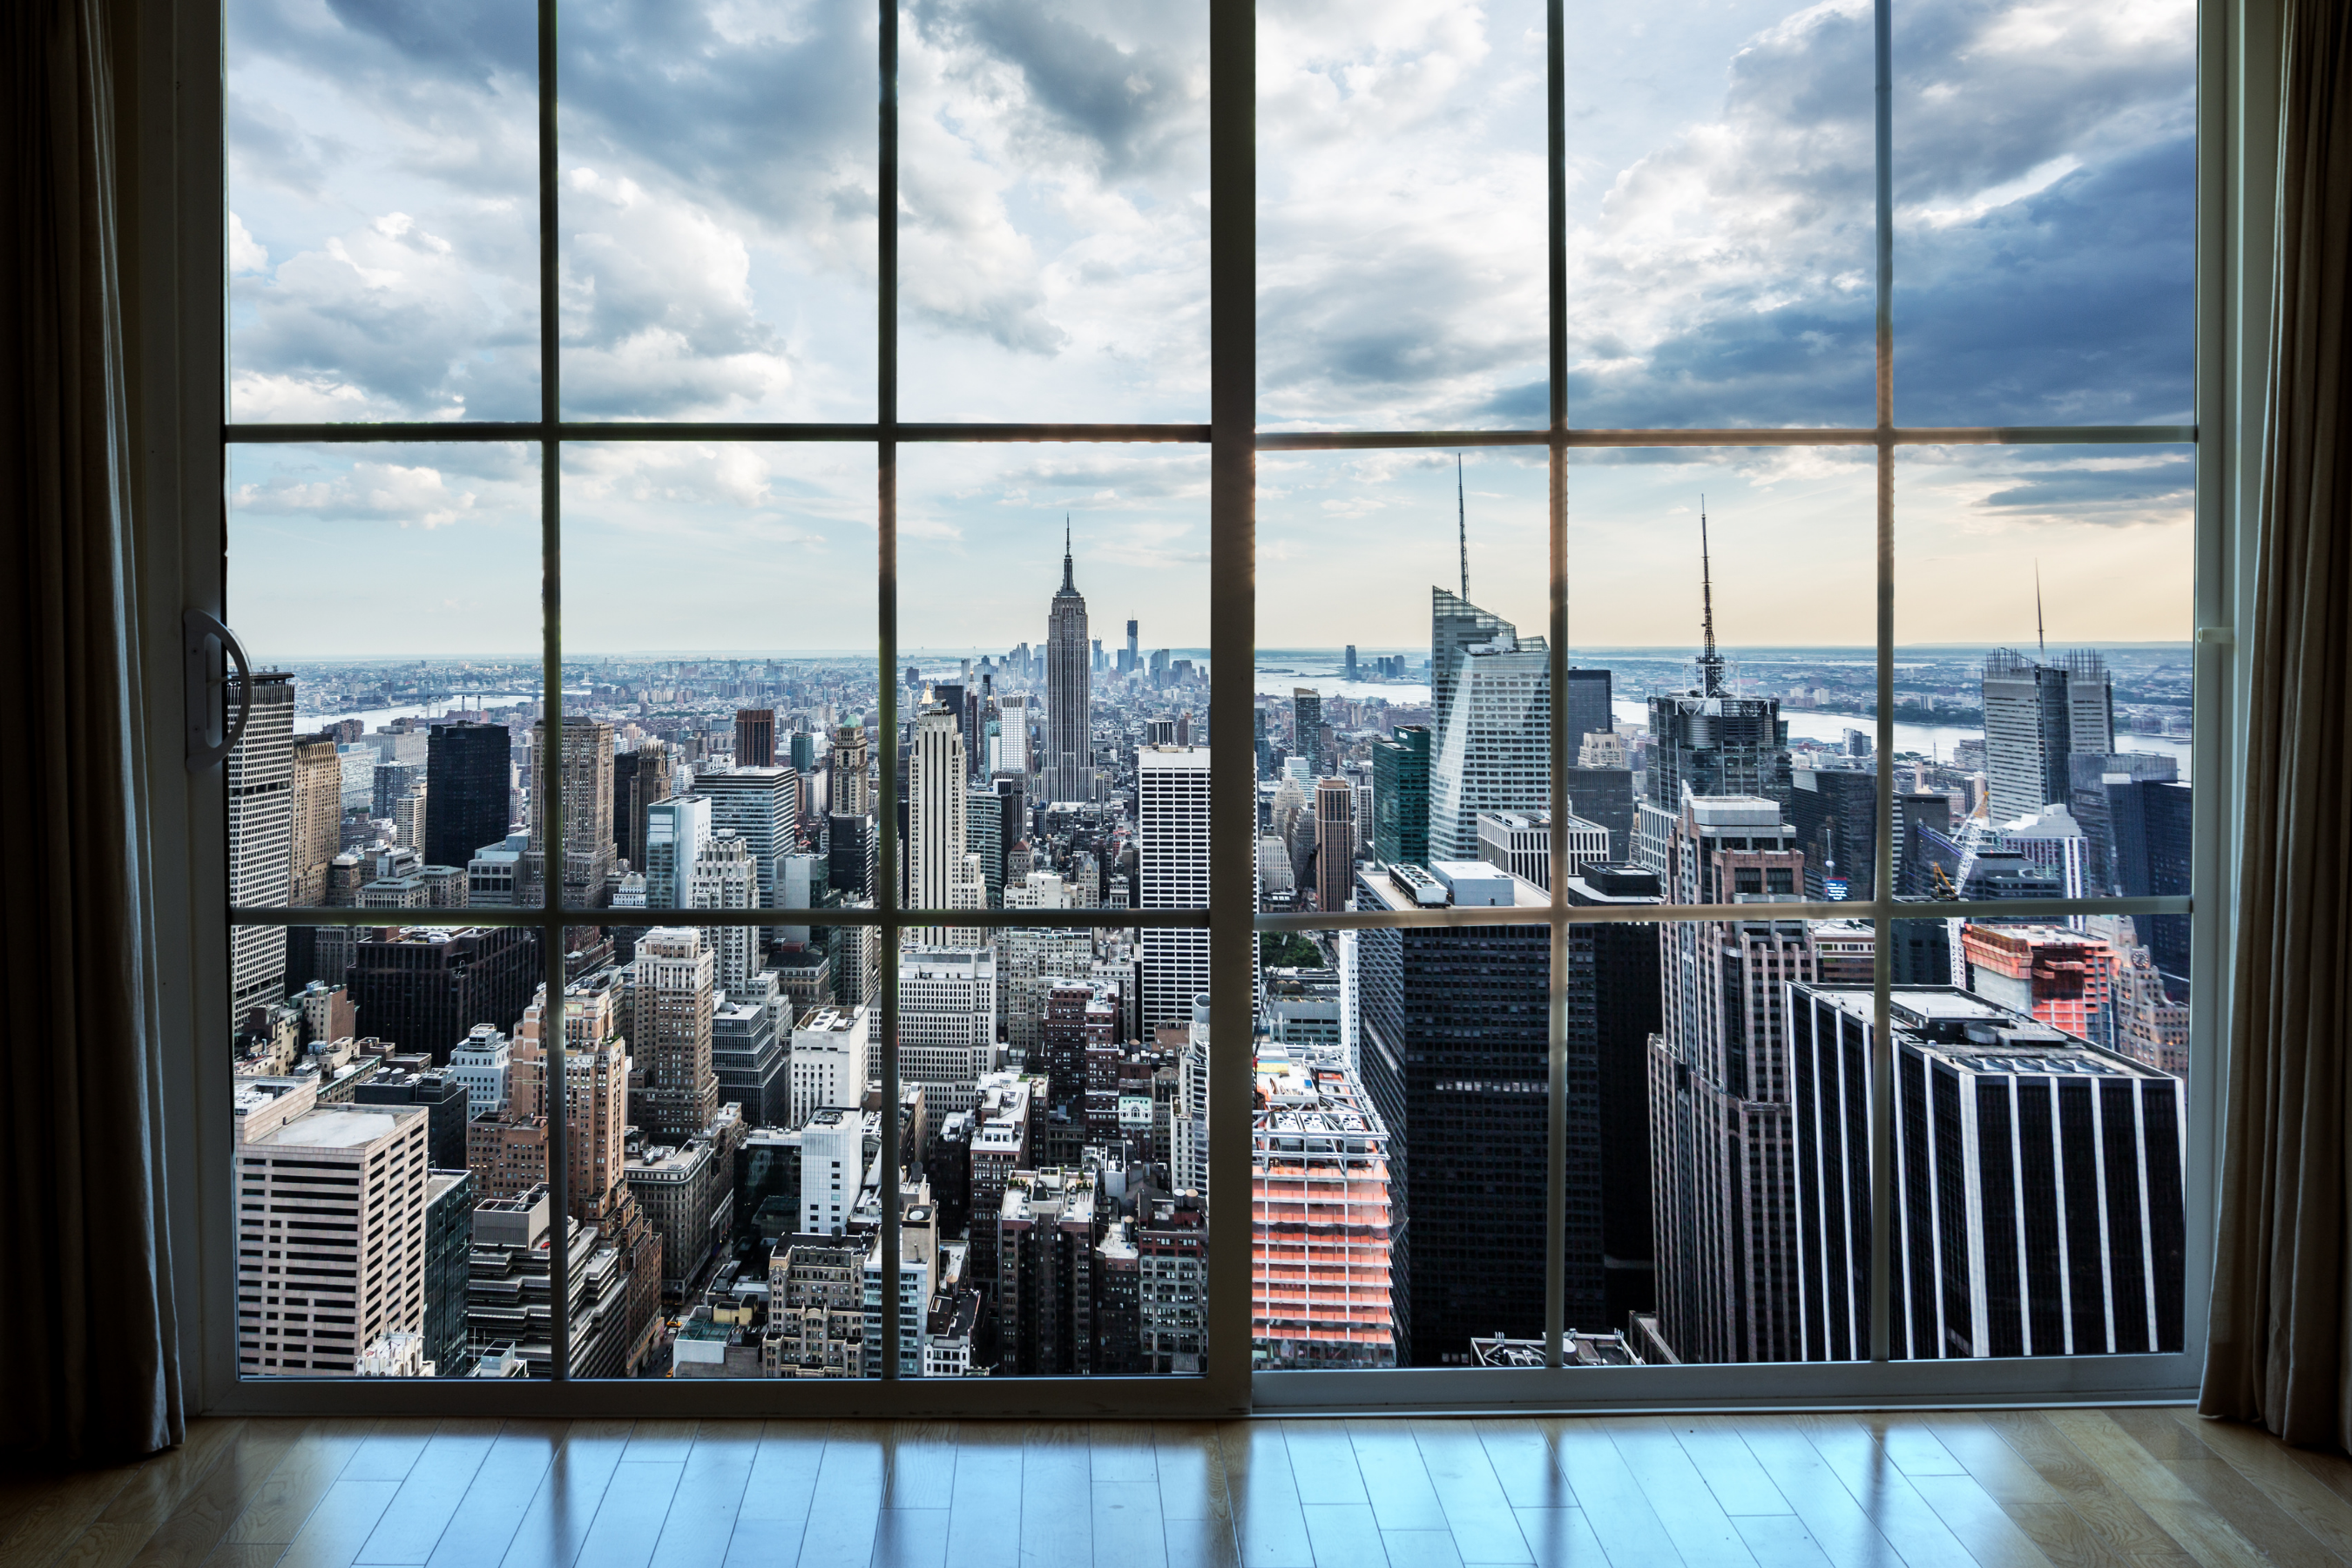
Describe the actual experience, not a forecast. Identify the room, approximate exposure, floor, window line, terrace or balcony, and the features visible from the unit when the description is prepared. If the horizon includes the river, harbor, bridges, skyline, historic fabric, or open sky, say what the buyer can see and from where. A phrase such as “southwest-facing living room with open Lower Manhattan and harbor outlooks at the time of marketing” is more defensible than “protected forever” or “nothing can ever be built.”
Avoid adjectives that imply legal status. “Protected view,” “unobstructed forever,” and “guaranteed panorama” may sound like sales language, but they invite a buyer to ask what instrument creates that protection. Unless a New York real estate attorney has confirmed a recorded right and its scope, do not use those terms. Even “unobstructed” should be tied to a photograph or inspection date, because construction, scaffolding, weather, foliage, lighting, and neighboring activity can change the appearance without any legal dispute.
New York’s Department of State advertising rule requires an honest and accurate depiction of the property and requires broker identification and other disclosures. The rule applies to websites, email, flyers, signs, and other promotion. The seller should therefore approve a written description, photo set, and caption strategy with the listing broker before publication. The Department of State advertising regulations are a useful primary reference, not a substitute for counsel.
Photos should be current, representative, and labeled when a perspective is materially enhanced. A wide-angle image can show a room beautifully, but it should not imply a view from a window that does not have that sightline. Keep the original files and dates. If the listing is refreshed months later, reassess whether the captions and images still describe current conditions.
Why a view earns attention, but not a promise
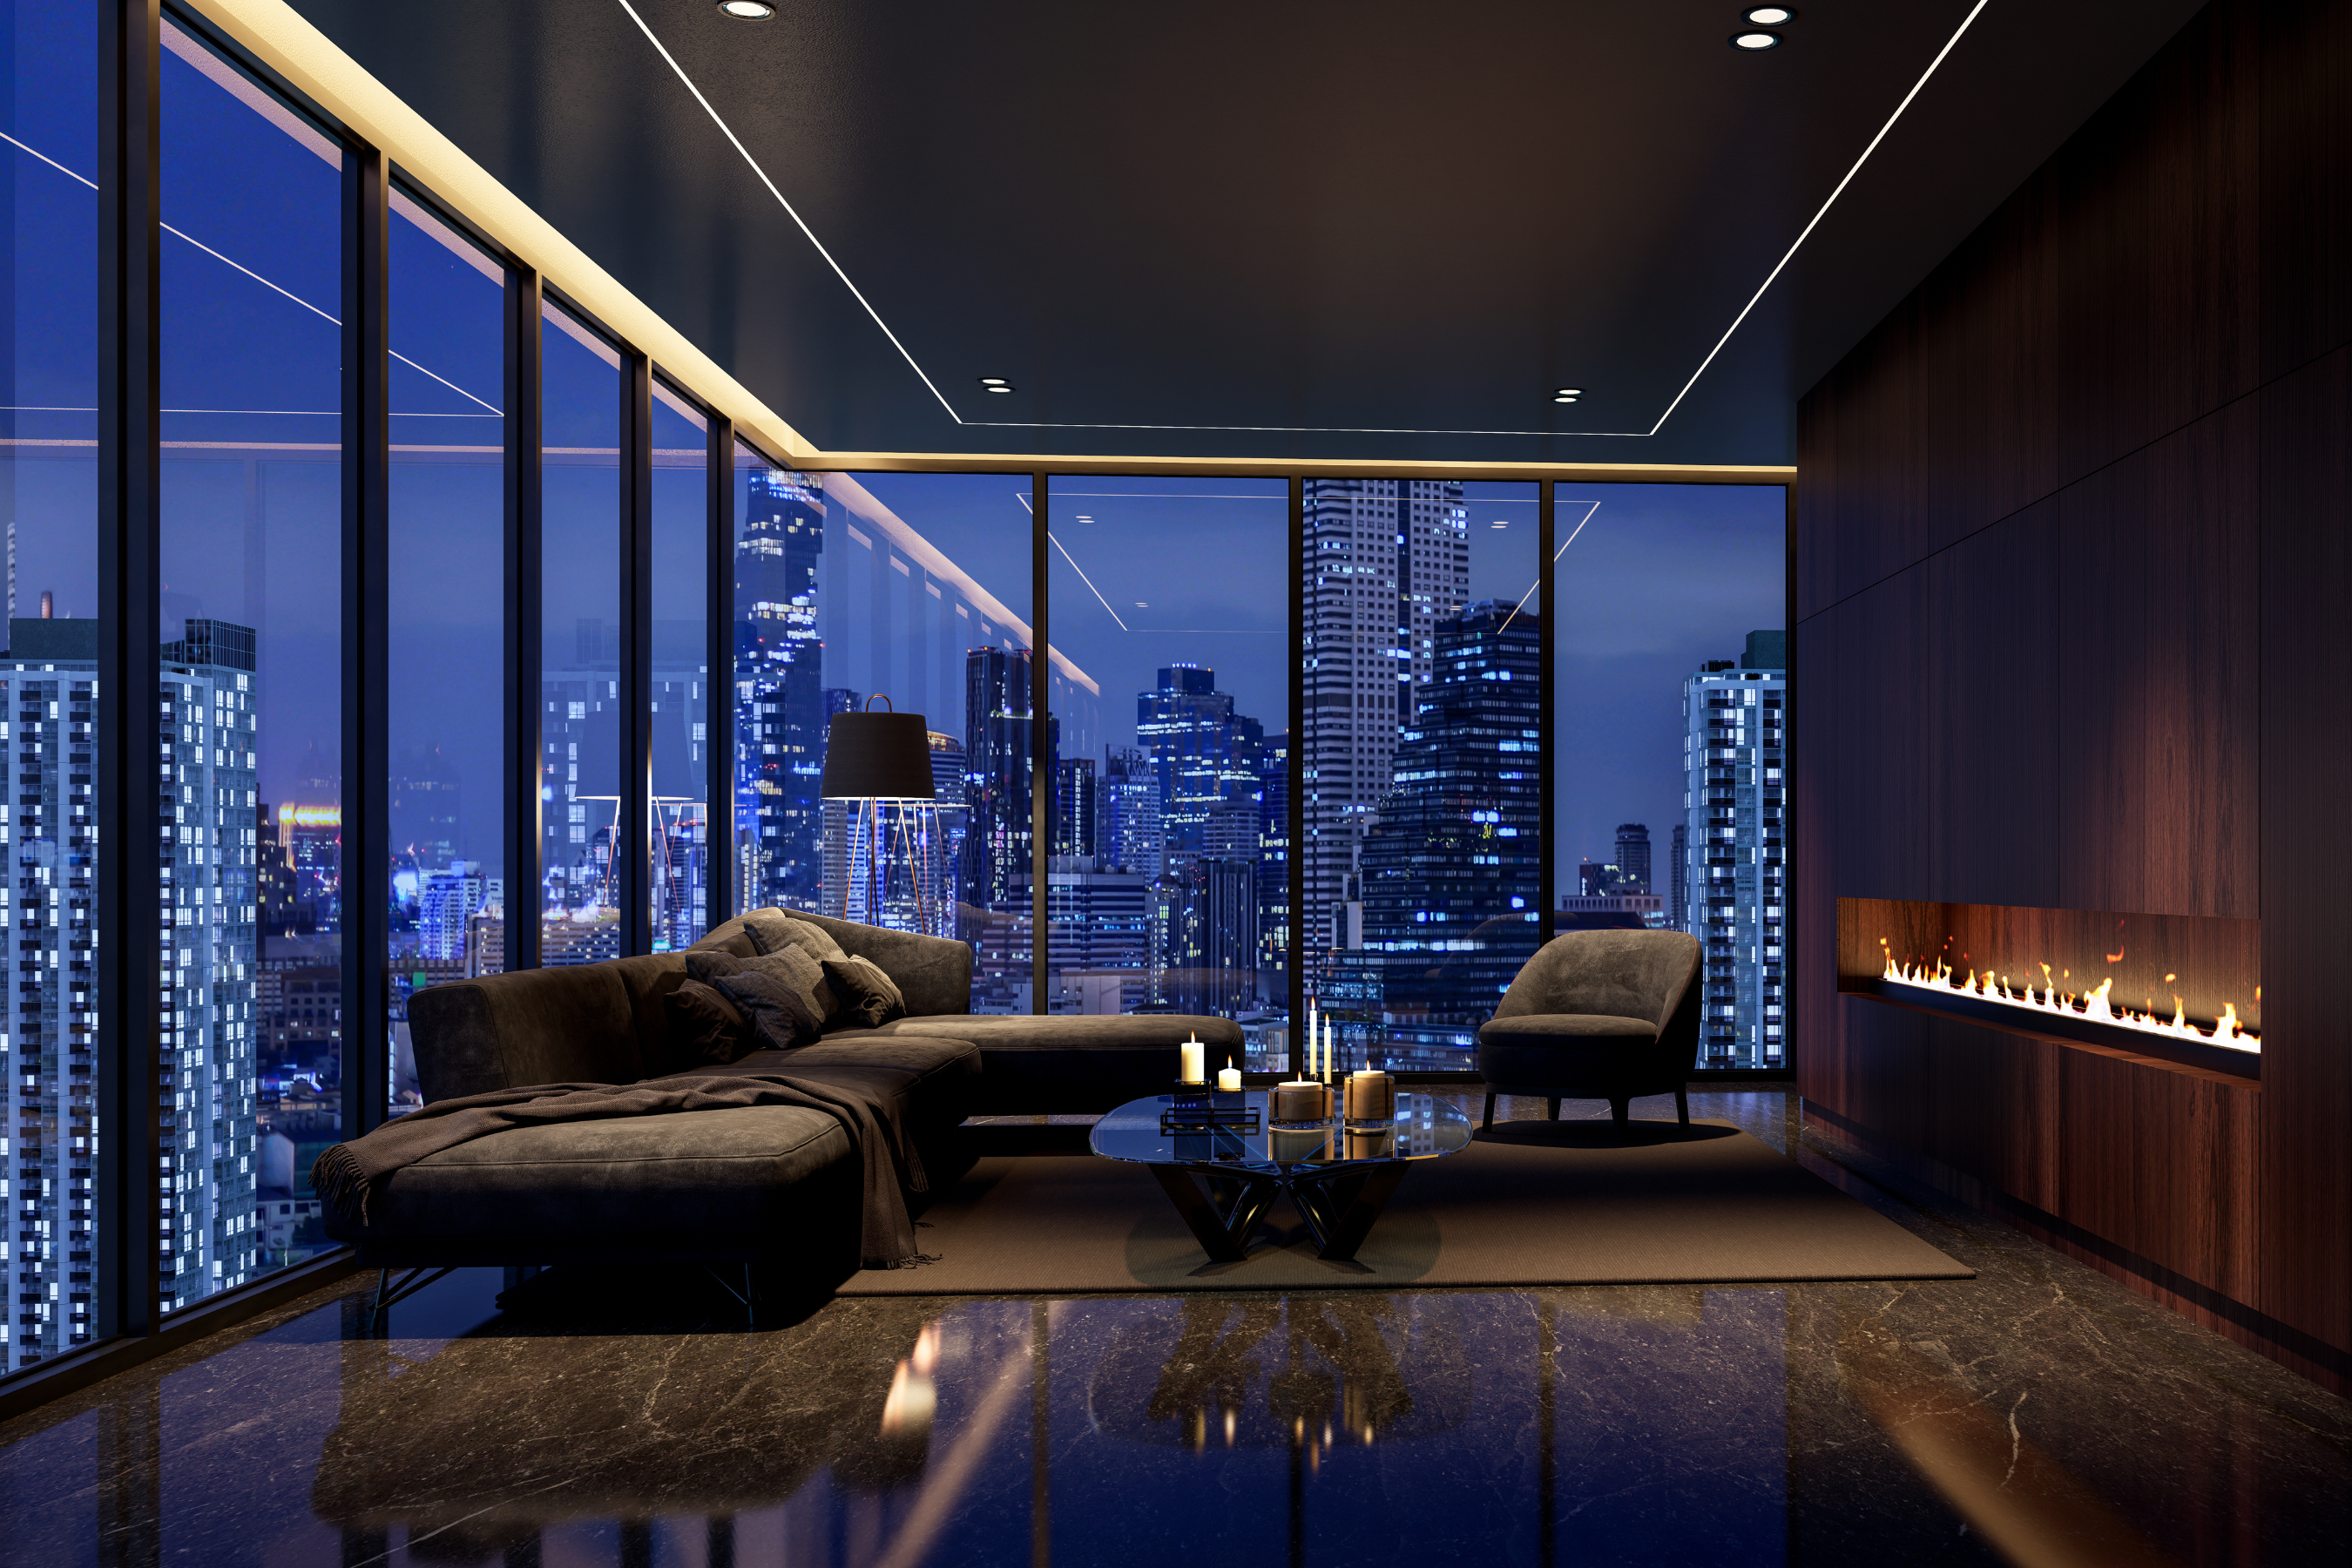
Buyer psychology makes an outlook powerful. A buyer may mentally rehearse morning light, a dinner with the skyline behind it, or the feeling of distance from street congestion. That emotional shortcut is useful, but it can also cause a buyer to overfocus on a picture and underweight carrying costs, building operations, financing, or resale liquidity. A seller’s job is not to eliminate emotion. It is to pair emotion with clear evidence.
A sophisticated presentation gives the view context. Show the sightline from ordinary standing and seated positions, identify which rooms benefit, and disclose whether the impression changes at night or in different seasons. Explain window direction in ordinary language and, where useful, provide a compass orientation or floor plan. A buyer can then compare an east-facing harbor glimpse with a broad western skyline outlook without being steered by a vague superlative.
The distinction between “current condition” and “future outcome” should be explicit. A photo may support what is visible today. It does not prove a vacant lot will remain vacant, that a public project will never change a waterfront setting, or that an adjacent building cannot be altered under applicable law. Conversely, the existence of a zoning envelope or planning study does not prove construction will occur or that a particular window will be blocked. Those are different propositions and should not be collapsed into a headline.
That balanced language can increase trust. Buyers who feel that the seller is hiding a question often widen their diligence, slow their offer, or demand a price concession. Buyers who see a clean evidence file can spend more time deciding whether the current outlook is worth the price. The strategy is not defensive disclosure for its own sake. It is confidence through precision.
Build a seller evidence file before launch
Start inside the condominium. Ask the managing agent or board, through the appropriate channel, for the current offering plan and amendments available to the owner, declaration, bylaws, rules, budget, common-charge schedule, capital-project information, and written notices affecting the unit or relevant common elements. A resale by an individual owner is not a new sponsor offering. The Attorney General explains that a resale is not regulated like a sponsor sale and may lack current building-condition information in an offering plan, so a buyer’s attorney may request board materials instead.
The Attorney General’s buyer guide recommends reading the entire offering plan and consulting an attorney before signing. Use the Attorney General offering plan database to identify filing, acceptance, effectiveness, sponsor, unit, and posted-document information. It is a starting point, not a substitute for reviewing the plan, amendments, declaration, or current building records.
Two FiDi examples illustrate why project identity should be verified. The Attorney General record for 50 West Street Condominium, plan CD130282, identifies 50 West Street as a new construction condominium accepted in 2014 and effective in 2016. The Attorney General record for The 130 William Street Condominium, plan CD180040, identifies 130 William Street as a new construction condominium accepted in 2018 and effective in 2019. The official 50 West project legal page identifies the plan file and says the sponsor makes no representation about future surrounding construction obstructing windows or terraces. The official 130 William project site describes the tower and residences. These records verify project identity and filing history, not a unit’s legal view protection.
Have counsel review any contract or rider representation. General Business Law section 352-e addresses covered public offerings and material information. Its focus is a sponsor offering, but the practical lesson is broader: do not omit or distort a material fact or repeat a sponsor brochure’s future-facing language as a resale warranty.
Investigate nearby records without predicting an outcome
A view review should be a records exercise, not neighborhood rumor. Check ACRIS for deeds, declarations, easements, covenants, and other recorded documents. The City Register guidance says records are public and warns that reviewing them is not a title search. A title company or attorney should handle legal conclusions.
Check the Department of Buildings. The City says BIS and DOB NOW show property histories, including permits, complaints, violations, applications, inspections, and occupancy information. The DOB building-data guide explains that the systems cover different filing streams and points to zoning diagrams. Search the subject building, the lot across the street, and other lots in the sightline. Save dates and statuses. A filing or diagram may be relevant, but does not prove a project will be built or affect a window.
Use ZoLa and the Zoning Resolution to understand districts, special-purpose rules, landmarks, and permitted bulk. Zoning describes what may be allowed under conditions, not what a developer will build. If a buyer asks whether a lot can rise to a certain height, refer the question to an architect, engineer, surveyor, title professional, or attorney rather than offering a conclusion from a map screenshot.
Public projects require the same restraint. The City’s Financial District and Seaport Climate Resilience Master Plan provides official design, construction, shoreline, and public-access information. A plan, concept, environmental review, or projected schedule is not a finding that a particular condo view will change. Describe a relevant project only with its current official status and date.
Price the outlook as a feature, not an insurance policy
Comparable sales should match the qualities buyers are actually paying for: floor, exposure, window line, terrace, condition, layout, light, privacy, common charges, taxes, amenities, and timing. A lower-floor apartment with a wider open view is not automatically comparable to a higher-floor apartment with a narrower but iconic glimpse. Your broker should separate the view premium from renovation, size, and scarcity rather than treating a single record sale as proof of value.
Use a written pricing hypothesis. For example, and only as a hypothetical, assume a 900-square-foot unit could support a $1,800,000 list price based on comparable sales, while a documented, wide open outlook might justify a hypothetical five percent positioning difference, or $90,000. That is not an appraisal, market fact, or guaranteed premium. Test it against buyer feedback, showing volume, offer quality, and the time competing units remain available. If a buyer discounts the unit because of uncertainty, ask whether the concern is a documented condition, a cost issue, or a general fear. Each requires a different response.
The cost side matters. New York City requires real property transfer tax on covered transfers, and the Department of Finance says a return generally must be filed within thirty days even when tax is zero. The NYC RPTT guidance identifies individual residential condominium units as a residential transfer type and sets out rates and filing rules. Have counsel and a tax adviser model transfer tax, mortgage payoff, broker compensation, attorney fees, adjustments, and building fees before choosing a list price. A beautiful view does not change net-proceeds arithmetic.
For a confidential discussion of this FiDi outlook, the pricing evidence, and the launch plan, contact TheNewYorkCityBroker.com/contact-me.
Seller Strategy: Make Uncertainty Manageable
The strongest strategy is a dated, two-track launch. Track one presents the current experience with clean photography, an orientation sketch, a measured floor plan, and a short caption that says what is visible and when it was documented. Track two is a diligence folder: offering-plan identification, relevant amendments, the declaration and bylaws, board or managing-agent materials the seller may lawfully share, ACRIS search results, DOB and DOB NOW searches, and zoning or public-project links with access dates. Give the buyer’s attorney room to conduct independent diligence rather than promising that the folder is complete.
Before launch, have counsel approve every sentence that could be read as a future guarantee. Have the broker compare the unit against active, in-contract, and recent sold alternatives with similar exposures. Stage for the eye line that matters, not just the widest camera angle. During showings, let buyers stand at the windows and ask practical questions. If a question cannot be answered, say so, identify the appropriate record or professional, and follow up in writing. If a buyer raises a possible neighboring project, do not argue from rumor. Confirm the public record, state what it says, and label what remains uncertain.
This approach serves buyer psychology. The buyer gets the emotional reward of the outlook and the cognitive reassurance of a process. The seller avoids turning a normal urban reality into an unsupported alarm or an implied warranty. It also improves negotiation: a documented present condition can be priced and compared; an undocumented promise becomes a source of retrade risk. Keep a version history of marketing materials so the file shows what was represented at each stage. Recheck dynamic records and captions before accepting an offer, and let attorneys resolve contract language, disclosures, title questions, and any representations that survive closing.
Prepare for the contract and closing conversation
A condo resale involves more than marketing. The buyer’s attorney may review title, declaration, bylaws, budgets, financial statements, insurance, assessments, litigation disclosures, permits, certificates of occupancy, and building questionnaires. Gather these early, answer factually, and avoid guessing about board decisions or future capital work. Give any known written notice concerning the unit or a relevant common element to counsel promptly.
The deed and recorded condominium documents must identify the unit and common interest. New York’s Condominium Act and Real Property Law section 339-o show why the legal unit description is not interchangeable with a marketing description.
At closing, coordinate with the title company, attorneys, managing agent, and buyer’s team on payoffs, transfer forms, move procedures, keys, access devices, and adjustments. ACRIS records Manhattan property documents and supports transfer-tax filing. Exact obligations vary and should be confirmed by counsel.
For owners planning a sale, the most useful mindset is neither “the view is guaranteed” nor “the view is doomed.” It is “the view is a present asset that deserves evidence, careful language, and a fair test in the market.” If you are selling a condo in the Financial District, begin with a property-specific review rather than a generic promise.
For a FiDi view-risk pricing and evidence plan, contact TheNewYorkCityBroker.com/contact-me.
This guide is general information, not a property-specific legal, title, zoning, engineering, tax, or appraisal opinion. Have the appropriate professionals review the actual unit and surrounding records before relying on a view-related claim.
Frequently Asked Questions
Only if a qualified attorney confirms a real, recorded protection and the wording accurately describes its scope. A view that is open today is not automatically a protected view. New York’s Department of State advertising rule requires an honest and accurate property depiction, and the Attorney General’s materials stress the importance of complete, accurate offering-plan information in sponsor offerings. Safer language identifies the room, exposure, floor, and visible features as observed on a stated date. Do not imply that zoning, a landmark, a park, a waterfront, or a vacant parcel guarantees a permanent outlook. Ask counsel to approve any phrase such as “protected,” “forever,” or “guaranteed.”
No. A zoning map and Zoning Resolution describe land-use and bulk rules, but a permitted building is not the same as an approved project, a filed application, a permit, construction, or a finished obstruction. DOB records can show applications, permits, violations, and other activity, while DOB NOW and BIS cover different records. Review the actual sightline and relevant lots, save dates and statuses, and avoid predicting an outcome. If the question affects value, a buyer should consult an architect, engineer, surveyor, title professional, and attorney. A seller can disclose a verified record without alleging that a view will change.
Ask the managing agent or board, through the building’s established process, for the current offering-plan materials and amendments available to the owner, declaration, bylaws, rules, budget, common-charge schedule, financial information, assessments, insurance information, litigation information, and building questionnaire requirements. The exact package depends on the building and transaction. A resale is not a sponsor sale, and the Attorney General notes that a resale offering plan may not be current or available. Do not circulate confidential records casually. Give the file to your attorney and broker so they can determine what may be shared and how to describe it.
Yes, in a limited and precise sense. The Attorney General record for 50 West Street Condominium and the record for The 130 William Street Condominium identify the projects at their respective Manhattan addresses. Each record describes a new-construction condominium offering plan with acceptance and effective dates. Official project pages identify the buildings. Those records verify project identity and filing history. They do not prove a unit’s present view, guarantee future conditions, or establish a legal view easement. Verify unit records and consult counsel before using either project as a comparable or making a view statement.
Start with comparable units that match floor, exposure, size, layout, condition, terrace, light, privacy, common charges, taxes, and timing. Separate the possible view premium from other features. Treat any percentage as a test, not a fact. For example, a hypothetical five percent adjustment on a hypothetical $1,800,000 baseline would be $90,000, but actual value depends on evidence and buyer response. Monitor showings, repeat visits, offers, and objections. If buyers focus on uncertainty, identify whether they mean a documented project, a cost concern, or a general fear. Your broker can reposition the price or presentation, while an appraiser and attorney address professional valuation and legal questions.
Use ACRIS for recorded deeds and other property documents, and remember the City warns that a public-record review is not the same as a title search. Check DOB BIS and DOB NOW for building filings, permits, complaints, violations, inspections, occupancy information, and available project material. Use ZoLa and the Zoning Resolution for land-use context, and review official public-project pages when a project is relevant. These tools support diligence but do not replace a title search, survey, inspection, engineering review, appraisal, or legal advice. Preserve dated records and marketing materials. The buyer should independently verify facts before signing.